


Our goal with The Daily Brief is to simplify the biggest stories in the Indian markets and help you understand what they mean. We won’t just tell you what happened; we’ll tell you why and how too. We do this show in both formats: video and audio. This piece curates the stories that we talk about.
You can listen to the podcast on Spotify, Apple Podcasts, or wherever you get your podcasts and watch the videos on YouTube. You can also watch The Daily Brief in Hindi.
In today’s edition of The Daily Brief:
1. The world sees a boom in Chinese yuan bonds
Global banks, multinationals, and sovereigns are issuing record volumes of Chinese yuan debt, with panda bond sales topping 210 billion yuan in eight months. The rush is fueled by wide yield spreads—China’s 10-year yield sits near 1.6% against US Treasuries above 5%. Yet this boom stems from domestic savers trapped behind capital controls rather than a structural threat to the dollar, which still holds 57% of global reserves against the yuan’s 2.1%.
2. What’s the right price for a plane ticket?
Surging festive airfares sparked Supreme Court scrutiny, but the new Bharatiya Vayuyan Niyam, 2026 preserves airline pricing freedom and limits regulatory intervention to crises. Though Indian passenger fares average a low 8 cents per kilometre, a $70 jet fuel crack spread and dollar costs threaten airlines with ₹38,000 crore in losses. With IndiGo and Air India dominating 90% of capacity and holding onto prime airport slots, seasonal supply constraints continue to price out flyers.
The world sees a boom in Chinese yuan bonds
Just recently, we saw a headline from Bloomberg columnist Andy Mukherjee that we couldn’t take our eyes off of. It stated that Western financial institutions and banks, which have always primarily raised debt in dollars or euros, are now issuing bonds denominated in the Chinese yuan like never before.

Many major American banks have doubled — even tripled — the issuance of dim-sum bonds, which are yuan-denominated bonds that originate in Hong Kong.
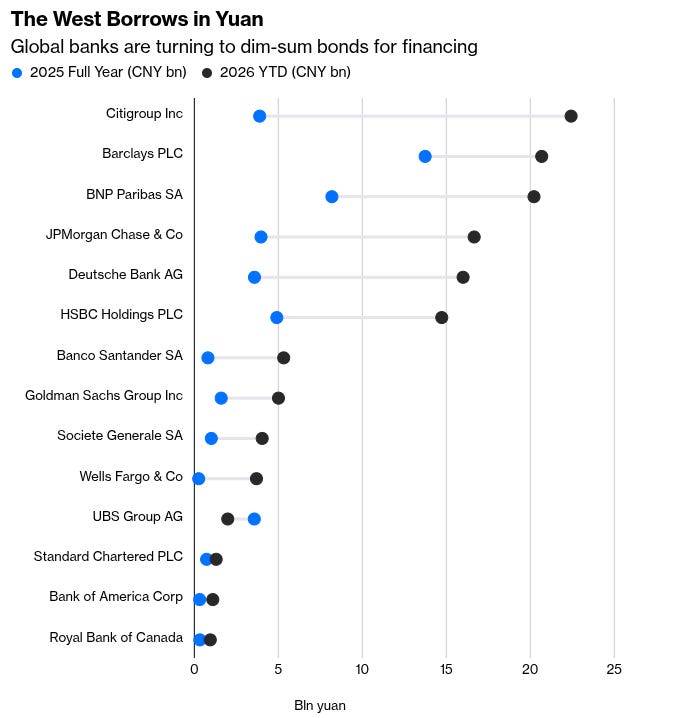
Besides the dim-sum bond, the panda bond — which is issued by foreign institutions and companies within mainland China — has also broken records this year. In just the first eight months of 2026, foreign borrowers raised over 210 billion yuan, which is more than the entire 2025 figure. Deutsche Bank alone raised a 5.5 billion yuan panda bond, the highest such issuance by a foreign bank.
The most important reason for this is price.
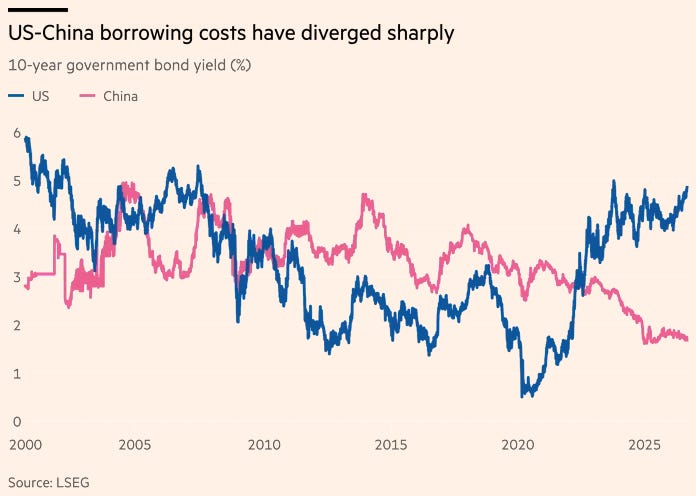
On one hand, yuan bonds have become cheaper themselves. Moreover, since 2022, dollar-denominated bonds have become much more expensive for their issuers.
When we looked deeper into it, we realized that the list of yuan bond issuers includes not just Western banks, but also multinational firms and entire governments. It’s tempting to read this as the dollar losing its grip on the world in favor of the yuan.
That being said, when you look at who is doing the lending in this boom, you mostly find the savings of Chinese households, who earn less than 1% on a one-year deposit at a big bank, and are shut out of the assets that yield better returns.
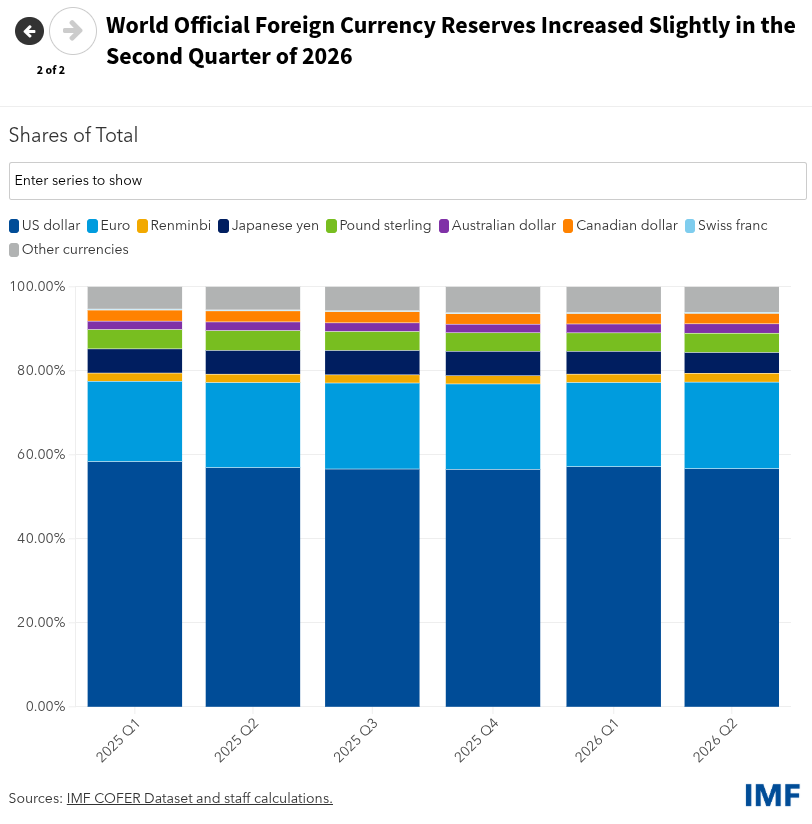
On top of all of that, China is still nowhere close to dislodging the dollar. The dollar makes up ~56.7% of global reserves, and the yuan just 2.1%.
Today, we’ll walk you through how this market works, why it’s suddenly booming, and what it really says about the world’s appetite for an alternative to the dollar.
The two yuans
At the start of this story, you might have wondered, “why are there two kinds of yuan bonds to begin with?”
The dim-sum bond is an offshore yuan bond, which is issued in Hong Kong. This can be issued by anyone and is freely tradable. The panda bond, however, is a more restrictive bond. It can only be issued by foreign entities, that too within mainland China, and can only be traded by institutions approved by the Chinese state.
The rationale behind this division has much to do with how China controls the flow of its own currency.
It’s no secret that with its growing footprint in world trade and investment, China wants the yuan to be used more around the world, and it has said as much. But a truly global currency (like the dollar today) needs capital to flow freely in and out of the country. China isn’t willing to allow that yet. It wants to stop money from fleeing the country in a panic, keep its exchange rate steady, and keep speculators from betting against the yuan.
So, China has tried to have it both ways, and this split explains the panda and the dim-sum bonds.
China keeps an onshore yuan (called CNY) walled off and tightly managed by the central bank. The panda bonds are issued in CNY. Alongside it, China has let a separate pool of yuan (called CNH) form outside the wall, mainly in Hong Kong, where it trades far more freely. The dim-sum bonds are issued in CNH.
The two pools are linked through state-approved channels, and usually, the CNY and CNH move along with each other. But because the wall stays up, they can drift apart, and Beijing can manage each one separately.
For instance, in January 2016, when traders were betting heavily on a falling yuan, Beijing drained yuan out of Hong Kong. The overnight cost of borrowing offshore yuan, which speculators needed to bet against it, shot to a record 66.8% in a single day, from 13.4%. The bet became too expensive to hold.
Dim-sum bonds are a little more expensive than panda bonds. For instance, the Indonesian government paid 2.5-2.9% on its dim-sum bonds, while onshore rates were running at 2.3-2.5%. Panda bonds are cheaper, but come with the wall’s rules. Dim-sum bonds are quicker and freer.
A clash of currencies
As we’d mentioned earlier, price is the key reason behind the surge in yuan bond issuances. But what exactly happened to the price? After all, for a long time, borrowing in yuan was more expensive than in dollars, and therefore hardly attractive.
Let’s start with the US side of the equation. Around 2022, to fight inflation, the US Federal Reserve raised rates at a speed not seen in decades. Then, in the last 2 years, investor uncertainty around Trump’s trade policies, and the threat posed to the independence of the Federal Reserve only added to the risk premium.
On the other end, with its property market slumping and domestic demand subdued, Beijing kept cutting its rates to kickstart the economy.
Somewhere in the middle of 2022, the two lines crossed, and once yuan became cheaper than dollars, borrowers started showing up. Panda issuance set records in 2023 and 2024. The dim-sum market nearly tripled between 2022 and 2024.
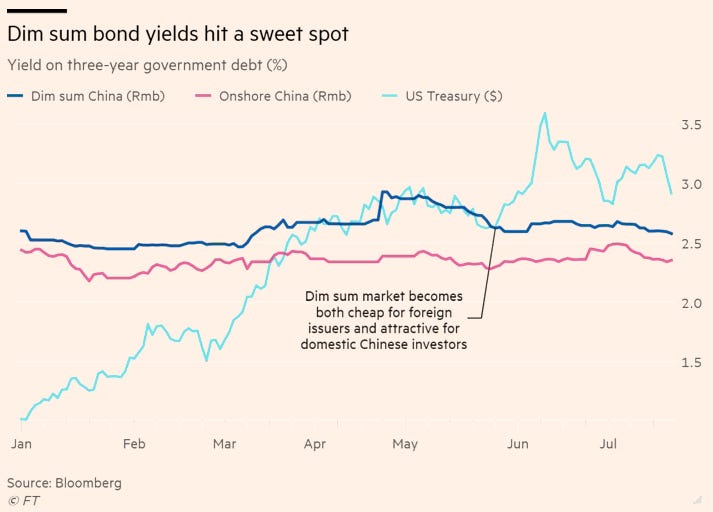
Today, China’s 10-year yield has sat at around 1.6%, while America’s 10-year bond yield touched 5.34% in early October — its highest since 2002. The gap has probably never been this wide before.
You can see this in what borrowers actually pay. According to one Chinese economist, big foreign banks have been selling panda bonds at roughly 1.7-2.2%, when the same money in dollars would cost them 4.5-5.5%.
The other reasons
Beyond price, there are two other reasons behind the newfound yuan bond boom.
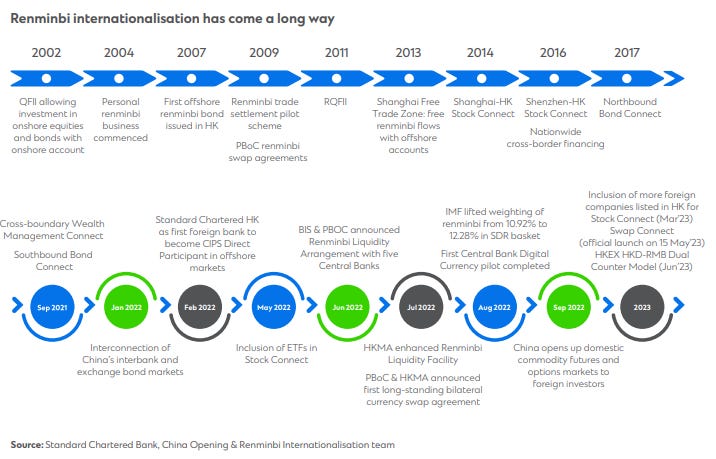
For one, the Chinese state has been slowly and steadily easing its rules around the flow of its currency, while still retaining an iron hand over it. Since 2010, they’ve been slowly opening up the onshore bond market. A rule that took effect in January 2023 allowed panda money to also be sent abroad, though still with limits and monitors.
The second reason has to do with geopolitics.
You see, right after the invasion of Ukraine, the US and Europe blocked the Russian central bank from accessing its dollar, euro and sterling pound reserves. That amounted to $300 billion, or almost half of the bank’s total foreign reserves at the time. The US has used similar sanctioning powers against others.
The episode made other governments wary of depending on Western finance. Indonesia, which made a major panda bond sale this year, has been explicit about this, with its finance minister saying:
“We continue to diversify so we’re not dependent on financing from the United States or Western countries”.
Who are the borrowers?
Now that we know why yuan borrowing has increased, let’s look at who’s doing the borrowing.
The domestic market
In the dim-sum market, the answer is….mostly China itself. Chinese companies and institutions account for about two-thirds of this year’s issuance. The list includes China’s finance ministry, state-owned giants like State Grid, tech firms like Baidu and Tencent, and provincial governments like Shenzhen and Guangdong.
Why would a Chinese company borrow in its own currency in Hong Kong? It may need the money outside China to fund operations abroad or to repay old dollar debt. Chinese institutions also used to raise money abroad through the dollar while US rates were low. But in the first half of 2026, their dollar bond sales abroad fell nearly 42%.
In other words, a large part of the dim-sum boom is Chinese savers lending to Chinese companies, with Hong Kong in the middle.
Foreign borrowers
The foreign borrowers are also growing at a fast pace, both for dim-sum and panda bonds. Their share of dim-sum issuance has risen to 35% from 23%. In the panda market, every borrower is foreign by definition.
But even within foreign borrowers, different actors will have different reasons.
Take multinational companies that operate in China, and consider it amongst their most important markets. For instance, German carmakers, among the most active panda issuers, use the money to run their Chinese operations. They borrow, spend, and earn income in yuan.
Then, there are sovereigns like Indonesia, Pakistan, and Kazakhstan, who don’t want to depend on dollar financing alone, or may simply want the cheapest offer available.
In fact, Portugal, which was the first Eurozone government to raise a dim-sum bond, had a simpler reason. They wanted to expand their investor base to include holders of Chinese capital. Chinese institutions rarely buy Portuguese euro bonds, but a yuan bond reaches money that Portugal wouldn’t be able to access otherwise.
Then, there are Western banks who may not need yuan per se. It’s simply cheap funding for them. Goldman, for instance, doesn’t use the money in China. It converts the yuan into dollars and hedges the currency risk by locking in the exchange rate. Even Portugal swapped its proceeds back into euros. However, this trick has been known to yield only modest savings of late.
Lastly, you have multilateral organizations like the World Bank and the Asian Development Bank (ADB). In fact, the first panda bond ever was actually issued by the World Bank’s IFC and ADB.
China’s savers are footing the bill
Every one of these bonds needs a buyer, which is most likely to be Chinese.
Start with panda bonds. Since they sit inside the wall, they’re bought almost entirely by Chinese banks, insurers, mutual funds and wealth managers. Foreigners can buy in through approved channels, but they hold less than 2% of China’s bonds overall.
Behind those institutions are ordinary savers, who bear the cost of how China controls its financing system.
See, China’s banks are known to pay paltry rates on fixed deposits because rates are deliberately kept low by the state. Then, Chinese households try to hunt for better returns, but they can’t buy bonds that trade on the interbank market (like panda bonds). So, they park their money in wealth products, funds and insurance policies, which then look for better assets like panda bonds, which pay only slightly more than a Chinese government bond.
Dim-sum bonds have a far more global set of buyers. Global funds and insurers have long been part of this market, and private banks have become important sellers. Given China’s strict controls on capital being sent out of its borders, the participation of Chinese institutions in bonds issued in Hong Kong was low.
However, that has been changing in the last 5 years. In 2021, China created a channel called “Southbound Bond Connect”, that let Chinese banks buy bonds in Hong Kong. In July 2025, it was widened to include brokerages, insurers and wealth managers. This July, its annual limit rose from 500 billion to 800 billion yuan.
For these institutions, the appeal is simple: offshore yuan pays more than onshore yuan, with no currency risk. How much of the dim-sum market they account for is unknown, since Southbound has never published data on who holds what. But Beijing keeps raising the limit, which suggests demand is there.
Either way, the chain is easy to trace. A family’s deposit becomes an insurance premium, which becomes a yuan bond sold by Goldman Sachs or Portugal.
Conclusion
The yuan is cheap to borrow partly because of the same walls that stop it from going global. China’s interest rates are low for several reasons: soft spending at home, low inflation, and a central bank sticking to a moderately loose policy.
Capital controls add to it by caging a vast pool of Chinese savings inside the country chasing too few safe assets, pushing yields down even further.
How long the boom lasts depends on the gap between US and Chinese rates. One part of that gap may represent the Chinese economy. But, as we’ve covered before, the other part reflects investors demanding more to hold America’s government debt because of uncertainty around its policies.
But a truly global currency needs more than a cheap price. It needs an open, fully convertible capital account, and China isn’t ready to give up that control. Until it does, the world can borrow in yuan. It just can’t quite use it.

What’s the right price for a plane ticket?
This Diwali, a one-way ticket on some routes cost what a round trip did a year ago. When a petitioner asked the Supreme Court to urgently hear a plea alleging 700% fare hikes, the bench refused: “Don’t travel by air.”
It’s the same court that, in January, called festive fares “exploitation” and pushed the government to act. The result is the Bharatiya Vayuyan Niyam, 2026, which takes effect on January 1. When the government said rules were coming, shares of IndiGo fell, until officials clarified there would be no price controls. The court examines the rules on November 16.
Underneath it all is a simple question: when is airfare too high? Start with how your fare gets decided today.
Who decides what you pay
India freed airfares from government control in 1994. Since then, airlines price using fare buckets. Each flight’s seats are split into price tiers, and as the flight fills up, software moves the remaining seats into costlier tiers. Airlines file these fare ranges with the regulator, the DGCA, whose Tariff Monitoring Unit checks that nobody charges outside them.
The catch is that the airline sets that ceiling itself. So a ₹20,000 Diwali ticket is usually perfectly legal, because it sits within a range the airline chose.
On paper, the regulator does have a stick. Rule 135 of the Aircraft Rules, 1937, lets the DGCA act if an airline sets an “excessive” or “predatory” fare, or behaves in an “oligopolistic” way. In practice, it has barely been used.
When the government has controlled prices, it has done so through blunt, temporary orders. During COVID, from May 2020 to August 2022, every domestic route had a minimum and a maximum fare. The ceiling protected passengers; the floor protected weaker airlines from a fare war. Then last December, IndiGo’s meltdown cancelled about 4,500 flights in ten days, and some Delhi--Mumbai tickets on rival airlines sold for over ₹28,000. The ministry capped economy fares by distance, from ₹7,500 to ₹18,000, until March this year.
The new rules
So what does the Bharatiya Vayuyan Niyam change? On how high your fare can go, very little.
Under Rule 192, airlines still set their own fares “based on factors, including the cost of operation”, and still file and publish them. There’s no cap, and nobody approves a fare. The parent law under which these new rules are being written allows the government to approve, disapprove or revise fares. But, it chose not to.
Three things do change.
First, slightly more disclosure. Airlines already have to show the total fare with taxes and fees broken out. The new rules add cancellation charges and refund conditions, and count baggage charges as part of the fare.
Second, the emergency brake is now written down. If the government believes “an extraordinary situation has arisen”, it can issue proportionate, time-bound directions on fares. It could already do this: last December, it imposed caps simply by invoking its “regulatory powers”, without naming a rule. What’s new is that the power and its limits are now spelled out. But nothing defines “extraordinary”. An airline collapsing? A 700% festive surge? No number triggers it.
Third, the regulator loses its everyday stick. The DGCA’s power to act against “excessive”, “predatory” or “oligopolistic” fares doesn’t carry over. It will monitor fares but can’t act on what it sees. So power over fares moves from a regulator that could act on any day to a ministry that can act only in an emergency.
Even a recent promise didn’t make it in. In October, an official told The Economic Times there would be strict surveillance to stop airlines from charging above their highest filed fare. The final rules don’t spell out any such ceiling.
Net, you get a bit more transparency and a clearer crisis brake. But on an ordinary Diwali, the regulator will have less power over a high fare than it has today, at least on paper. So the rules don’t answer the court’s question. To judge whether a fare is too high, we think there are three honest tests.
Test one: Is the fare higher than what it costs to fly you?
Flying has got pricier, and not just at Diwali. By early 2024, domestic fares were 43% above 2019 levels. In the first half of 2026, economy fares rose at their sharpest pace since the COVID caps came off, per Cirium.
But airline costs have risen even faster. As we explained in our recent piece on IndiGo, jet fuel now costs about $70 a barrel more than crude, against roughly $11 through 2016--21. Indian taxes amplify every jump: jet fuel sits outside GST, attracting about 11% excise plus state VAT of up to 25--29%, none of which airlines can claim back. And leases, parts and much of maintenance are paid in dollars, so a weaker rupee makes all of it costlier.
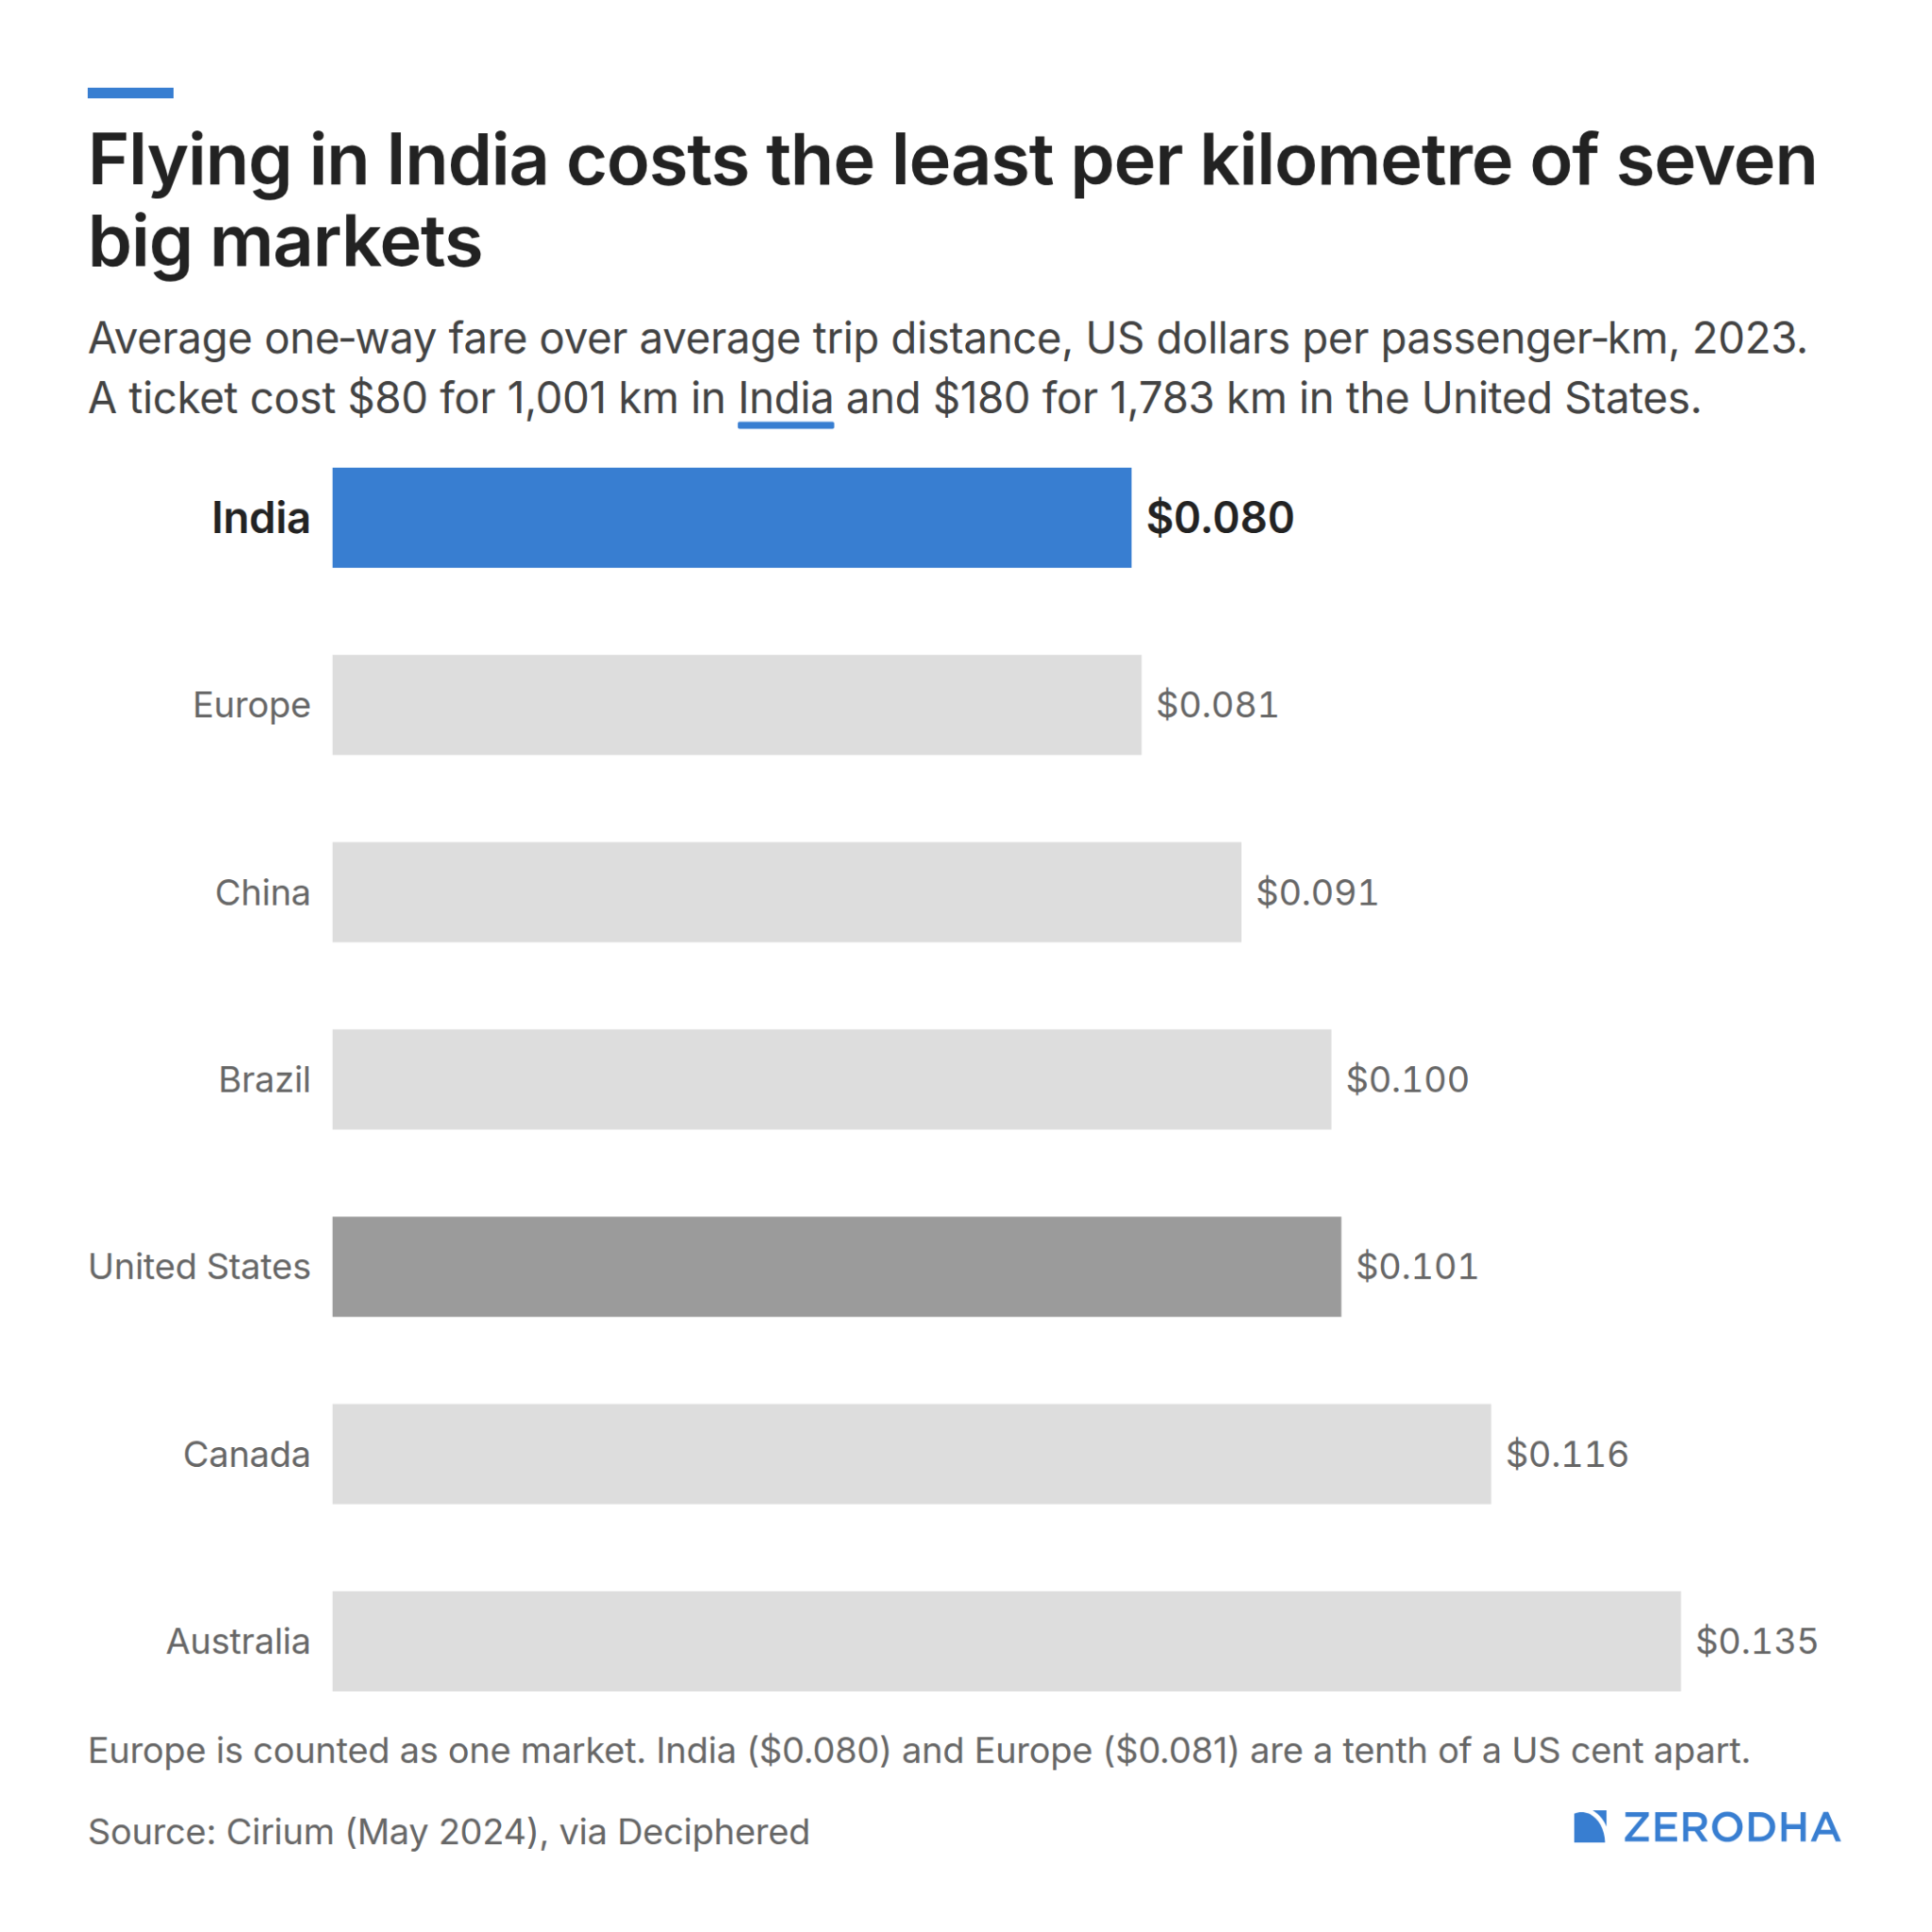
The result: ICRA expects Indian airlines to lose ₹36,000--38,000 crore this year. And they’re losing money despite selling some of the cheapest tickets in the world. Cirium data puts India at about 8 cents per passenger-kilometre in 2023, the lowest of seven major markets. The US, supposedly the land of cheap domestic flights, was at about 10 cents.
Airlines use this to argue that higher fares are simply costs being passed on. IndiGo CEO Willie Walsh says the link works both ways: “as fuel prices come down, ticket prices come down.” Co-founder Rahul Bhatia has said IndiGo could pass on only part of the fuel increase.
But “the industry is losing money” hides an important difference. IndiGo isn’t fighting for survival. Its FY26 loss becomes a profit once you strip out currency losses and a one-time labour-law charge. The war has only now reached its core business: it lost about ₹700 crore in the July--September quarter even setting currency aside, though that’s the industry’s weakest season. The rest of the industry was losing money well before the war; the Air India group alone lost ₹22,238 crore last year.
So on the cost test, the typical Indian fare isn’t a rip-off. But an average hides the spikes. And one reliably profitable airline surrounded by loss-making rivals is a clue we’ll come back to.
Test two: Who gets priced out, and when?
The spikes hit when people most need to fly. Fares for travel between September 1 and November 10 were up 68% on Delhi--Hyderabad, according to OAG.
You’d expect airlines to add flights in peak season. Instead, they flew less. Across October and November, they scheduled about 6% fewer flights than a year earlier, the first such drop since 2020. Patna, right before Chhath, lost about a fifth of its weekly departures.
Why? Because of a loop. Costlier fuel forces fares up. Higher fares push some people off planes. But a flight costs about the same to run with 80 passengers as with 180, so flying half-empty planes burns money. So airlines cut flights. Fewer flights mean fewer seats, and fewer seats push fares up again.
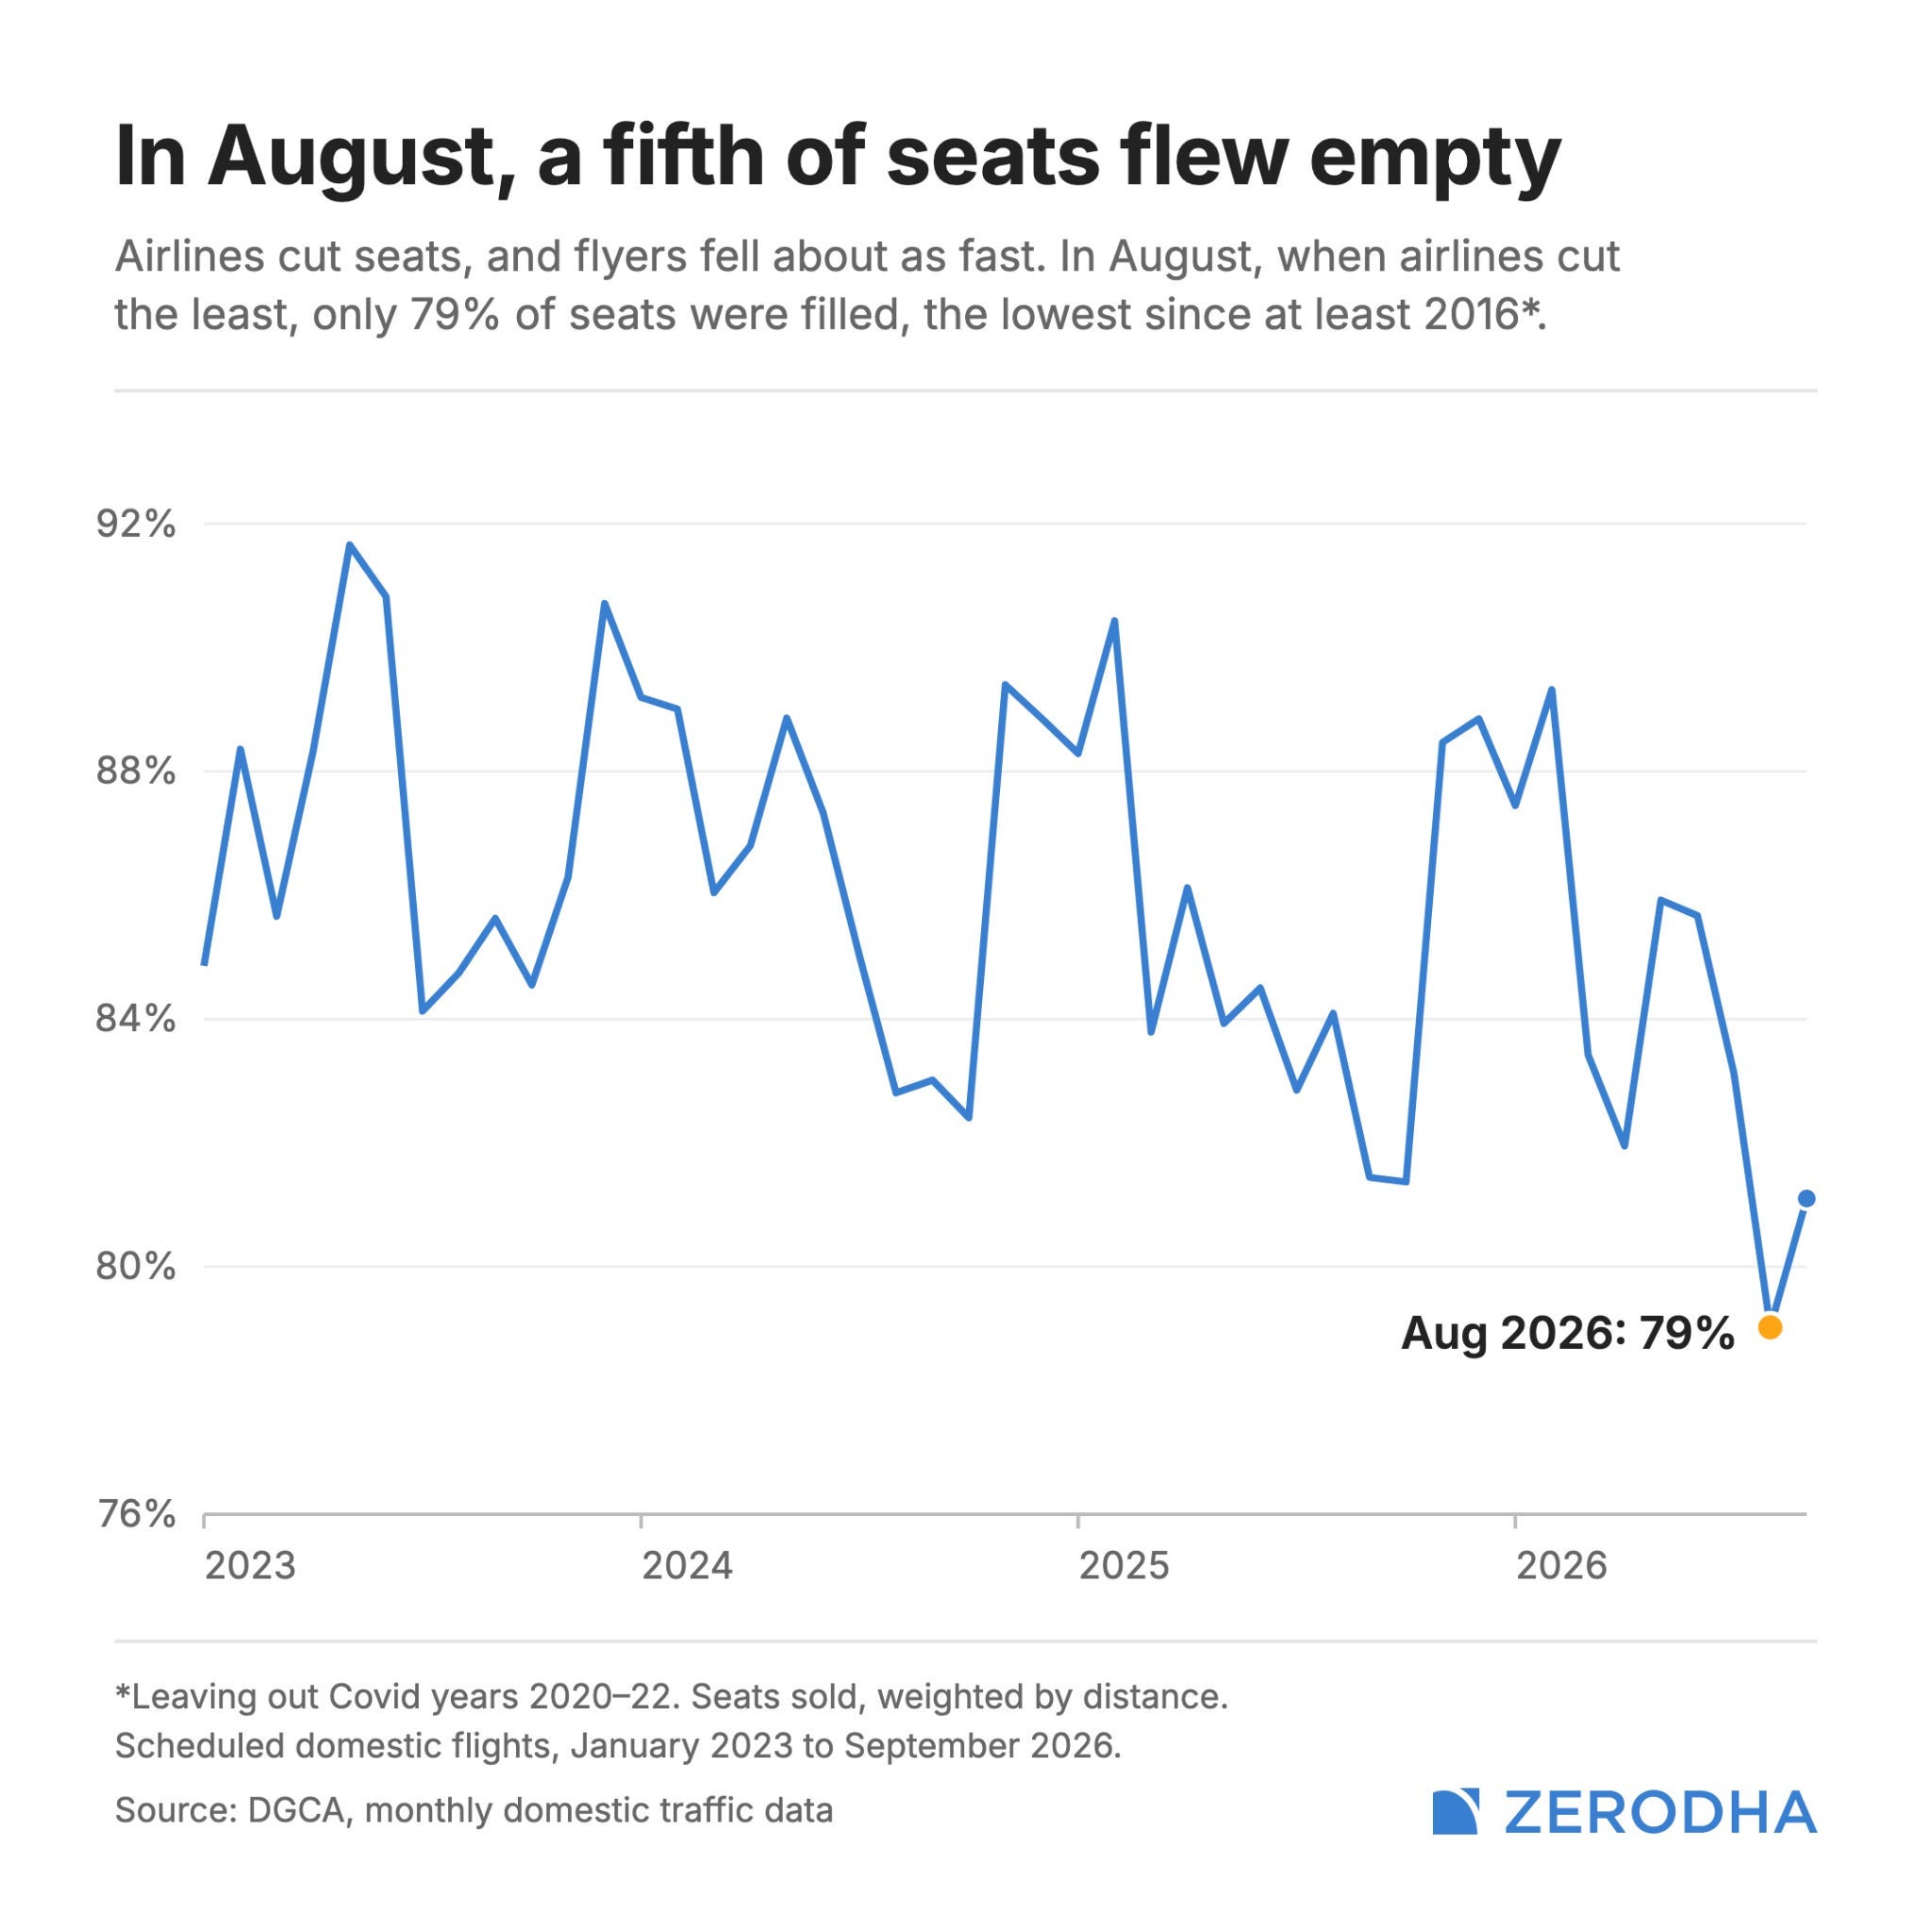
We traced this loop in the data. From June to September, flyers fell about as fast as seats, so planes didn’t get any fuller. In August, when airlines cut the fewest flights, only 79% of seats were filled, the lowest for a non-COVID month since at least 2016. By September, domestic flyers were down 6.5% from a year earlier.
And the pain isn’t evenly spread. On the three busiest business routes, flyers actually rose 7% in September, while on all other routes they fell 8%. With fewer planes to go around, airlines are putting them where people have to fly anyway. And it’s economy travellers who are absorbing the increase: in June, economy fares on Delhi--Srinagar were 85% higher than a year earlier, while business-class fares on the same route fell 20%.
So the bill lands on those with the least room to say no, like the worker going home for Chhath or the family that can’t skip Diwali. That’s exactly who a price cap is meant to protect. But before reaching for one, it’s worth asking why India’s peaks get this steep.
Test three: What happens when a rival shows up, or leaves?
IndiGo and the Air India group carry about nine in ten domestic flyers, and in June IndiGo’s own share hit a record 66.3%. That still understates it. By late 2025, IndiGo was the only airline on more than 500 city pairs.
Fewer rivals mean steeper peaks. Across Asia-Pacific and the Middle East, Airports Council International found that fares on single-airline routes rose over 25%, against about 10% on competitive ones. It works in reverse too: a month after Go First stopped flying in 2023, the average last-minute Delhi--Mumbai fare had tripled.
So why don’t new rivals show up?
Start with slots. Incumbents hold the takeoff and landing slots at crowded airports indefinitely. As the Takshashila Institution’s Anupam Manur puts it, a newcomer can cut fares but “cannot get a 7 a.m. Delhi--Bengaluru prime slot.” New airlines also queue for years behind giant aircraft orders, must fly a fixed share of loss-making regional routes that only a big fleet can absorb, and wait six months for any pilot they hire away. And when an airline collapses, its slots go to whoever already has planes, so every failure since 2007 has concentrated the market further. No wonder the three airlines cleared to fly last December are still grounded.
Here’s the irony. The strongest price safeguard in a crisis now comes from competition law, not aviation rules. After December’s meltdown, the Competition Commission probed whether IndiGo abused its dominance. To settle the case, IndiGo offered, among other things, not to charge above its filed fare ranges during a large-scale disruption. That’s the very ceiling the new rules don’t spell out.
Treat the cause, not the symptom
So what’s the right price for a plane ticket? The one a market with real competition would produce. A price Indonesia learned this the hard way. When it cut fare ceilings in its two-airline market in 2019, airlines simply cut seats, and fares rose anyway. The US, which stopped setting fares in 1978, instead keeps them in check by blocking mergers that would wipe out competition.
The tests point to two root causes: high costs and too few rivals. Yet India’s interventions have been almost entirely on price. The cost side has had only stopgaps, like a few months of restrained jet fuel prices and lower fuel VAT in Delhi and Maharashtra.
The lasting fixes aren’t in Rule 192. Bringing jet fuel under GST would cut a cost that swells every time oil does, though states resist losing the revenue. Getting more airlines flying means treating slots as a public resource, so a failed airline’s slots go to newcomers rather than the biggest player. It means faster insolvency, more pilot training, and rules that don’t punish an airline for being small.
On November 16, the Supreme Court will look at a rule built for emergencies. The problem shows up every Diwali.
- This edition of the newsletter was written by Manie & Kashish.
Tidbits:
1. Blackstone to invest ₹5,000 crore in IIFL Finance for about a 16% stake
Blackstone will invest ₹5,000 crore in IIFL Finance for about a 16% stake on a fully diluted basis. IIFL’s promoters and Anchorage Capital will invest another ₹1,414 crore, taking the total capital raise to ₹6,414 crore. The fresh capital is expected to strengthen the lender’s balance sheet and support future growth.
Source: Business Standard
2. Patna Municipal Corporation lists ₹200 crore municipal bonds on NSE
Patna Municipal Corporation has listed ₹200 crore of municipal bonds on the National Stock Exchange, becoming the first civic body in Bihar to tap the bond market. The 10-year bonds carry an annual interest rate of 9.2%, and the money will fund infrastructure projects across 15 locations in Patna.
Source: Hindu Businessline
3. Centre makes weekly rice and paddy stock disclosures mandatory
The government has ordered traders, retailers and millers across India to report their rice and paddy stocks every Friday. It has also doubled its rice sale target under the Open Market Sale Scheme from 25 lakh tonnes to 50 lakh tonnes for FY27. Five southern states can also impose stock limits until January 31, 2027, if needed.
Source: Print
4. TSMC plans to invest up to $1 billion in Anthropic and OpenAI
TSMC plans to invest up to $500 million each in Anthropic and OpenAI. Its board approved buying Anthropic shares at its IPO price, and OpenAI preferred stock, giving the world’s largest contract chipmaker direct stakes in two major AI companies.
Source: Reuters
5. Government extends medical devices PLI scheme to FY36
The government has extended the production-linked incentive scheme for medical devices by eight years to FY36. The revised scheme removes the minimum sales threshold, lowers investment requirements and offers higher incentives for critical components and high-end medical devices.
Source: Business Standard
Want more tidbits? Catch up on last week’s recap!

Beyond Today’s Brief
There’s always more happening at Markets by Zerodha.
The Chatter: Why is SEBI mandating mutual fund direct plans as the digital default while the RBI flags shifting household savings preferences and deposit franchise risks? And how are Bharti Airtel, Tata Steel, Hindalco, LG Electronics, and ONGC driving massive structural bets—from 1 GW data centre expansions and European steel margin turnarounds to ₹5,000 crore appliance manufacturing hubs and direct crude offtake rights in Venezuela?
Aftermarket Report: How did Nifty keep its winning momentum alive to close above 25,250 at 25,255 as cooling oil prices near $90 per barrel and Bank Nifty’s surge to within 1.5% of record highs helped absorb second-half selling? And what do 11 gaining sectors led by PSU Banks, eight straight sessions of foreign institutional buying, and the Fear & Greed Index advancing to 69 indicate as 13 of 15 sectors trade above all four key trendlines?
Join us on WhatsApp, where we share interesting soundbites from concalls, articles, and everything else we come across throughout the day. You’ll also get notified the moment a new video or article drops so that you can read or watch it right away.
Thank you for reading. Do share this with your friends and make them as smart as you are 😉
The distinction between onshore panda bonds and offshore dim-sum bonds is important when interpreting the issuance boom. A lower yuan yield can attract borrowers without proving that the currency is displacing the dollar in global reserves. For a borrower whose revenues are in another currency, the cost and availability of hedging also matter alongside the headline coupon. How much of the recent issuance reflects natural yuan funding needs versus borrowers swapping the proceeds into another currency?
Good piece. The number that stayed with me is the gap itself. China ten year at about 1.6 percent, the US ten year at 5.34 percent in early October. When borrowing in yuan costs a third of borrowing in dollars, the boom needs no grand story about the dollar losing its crown. It is arithmetic. The part I keep thinking about is who pays for the cheap price. Chinese savers earn under 1 percent on a one year deposit while their savings fund the bonds, so the subsidy runs from households to borrowers. That is why I read this as a funding trade, not a reserve currency shift. The dollar is still about 57 percent of global reserves. The boom lasts exactly as long as the rate gap does, and after a hot CPI print that gap is the thing to watch.