


Our goal with The Daily Brief is to simplify the biggest stories in the Indian markets and help you understand what they mean. We won’t just tell you what happened; we’ll tell you why and how too. We do this show in both formats: video and audio. This piece curates the stories that we talk about.
You can listen to the podcast on Spotify, Apple Podcasts, or wherever you get your podcasts and watch the videos on YouTube. You can also watch The Daily Brief in Hindi.
In today’s edition of The Daily Brief:
1. Taking stock of stock exchanges
Reporting financial results side-by-side for the first time since NSE’s IPO, India’s two leading bourses saw quarterly revenues slip 8.5% to 11% following low volatility and disruptions from SEBI’s now-reversed Closing Auction Session. While NSE operates as a near-monopoly handling over 90% of cash trading and generating 42% of revenue from weekly Nifty options alone, BSE has established a profitable niche by capturing low-premium expiry-day trading volumes where flexible costs buffer margins. With transaction fees driving over 74% of revenue, both exchanges are actively scaling data feeds, colocation racks, and commodities to build long-term streams beyond equity derivatives.
2. Carlsberg India’s IPO rests on one strong beer
Filing draft prospectus papers for an offer-for-sale IPO of up to ₹6,660 crore, Carlsberg India reveals a brewing business overwhelmingly carried by a single mainstream product: Tuborg Strong, which delivers roughly 70% of gross sales. More than half of reported revenues go straight to state excise departments, while packaging outspends brewing ingredients three to one. Although premium margins and lower presence in price-controlled southern states have historically allowed Carlsberg to generate more profit than market leader United Breweries on a third of the volume, recent input inflation, state distributor delays, and brand concentration underline significant operational risks.
Taking stock of stock exchanges
Almost every trade you place in India ends up at NSE or BSE. They match your order with someone else’s, make sure the trade settles, and take a small cut. BSE has been listed since 2017, but NSE, the far bigger of the two, only went public this September.
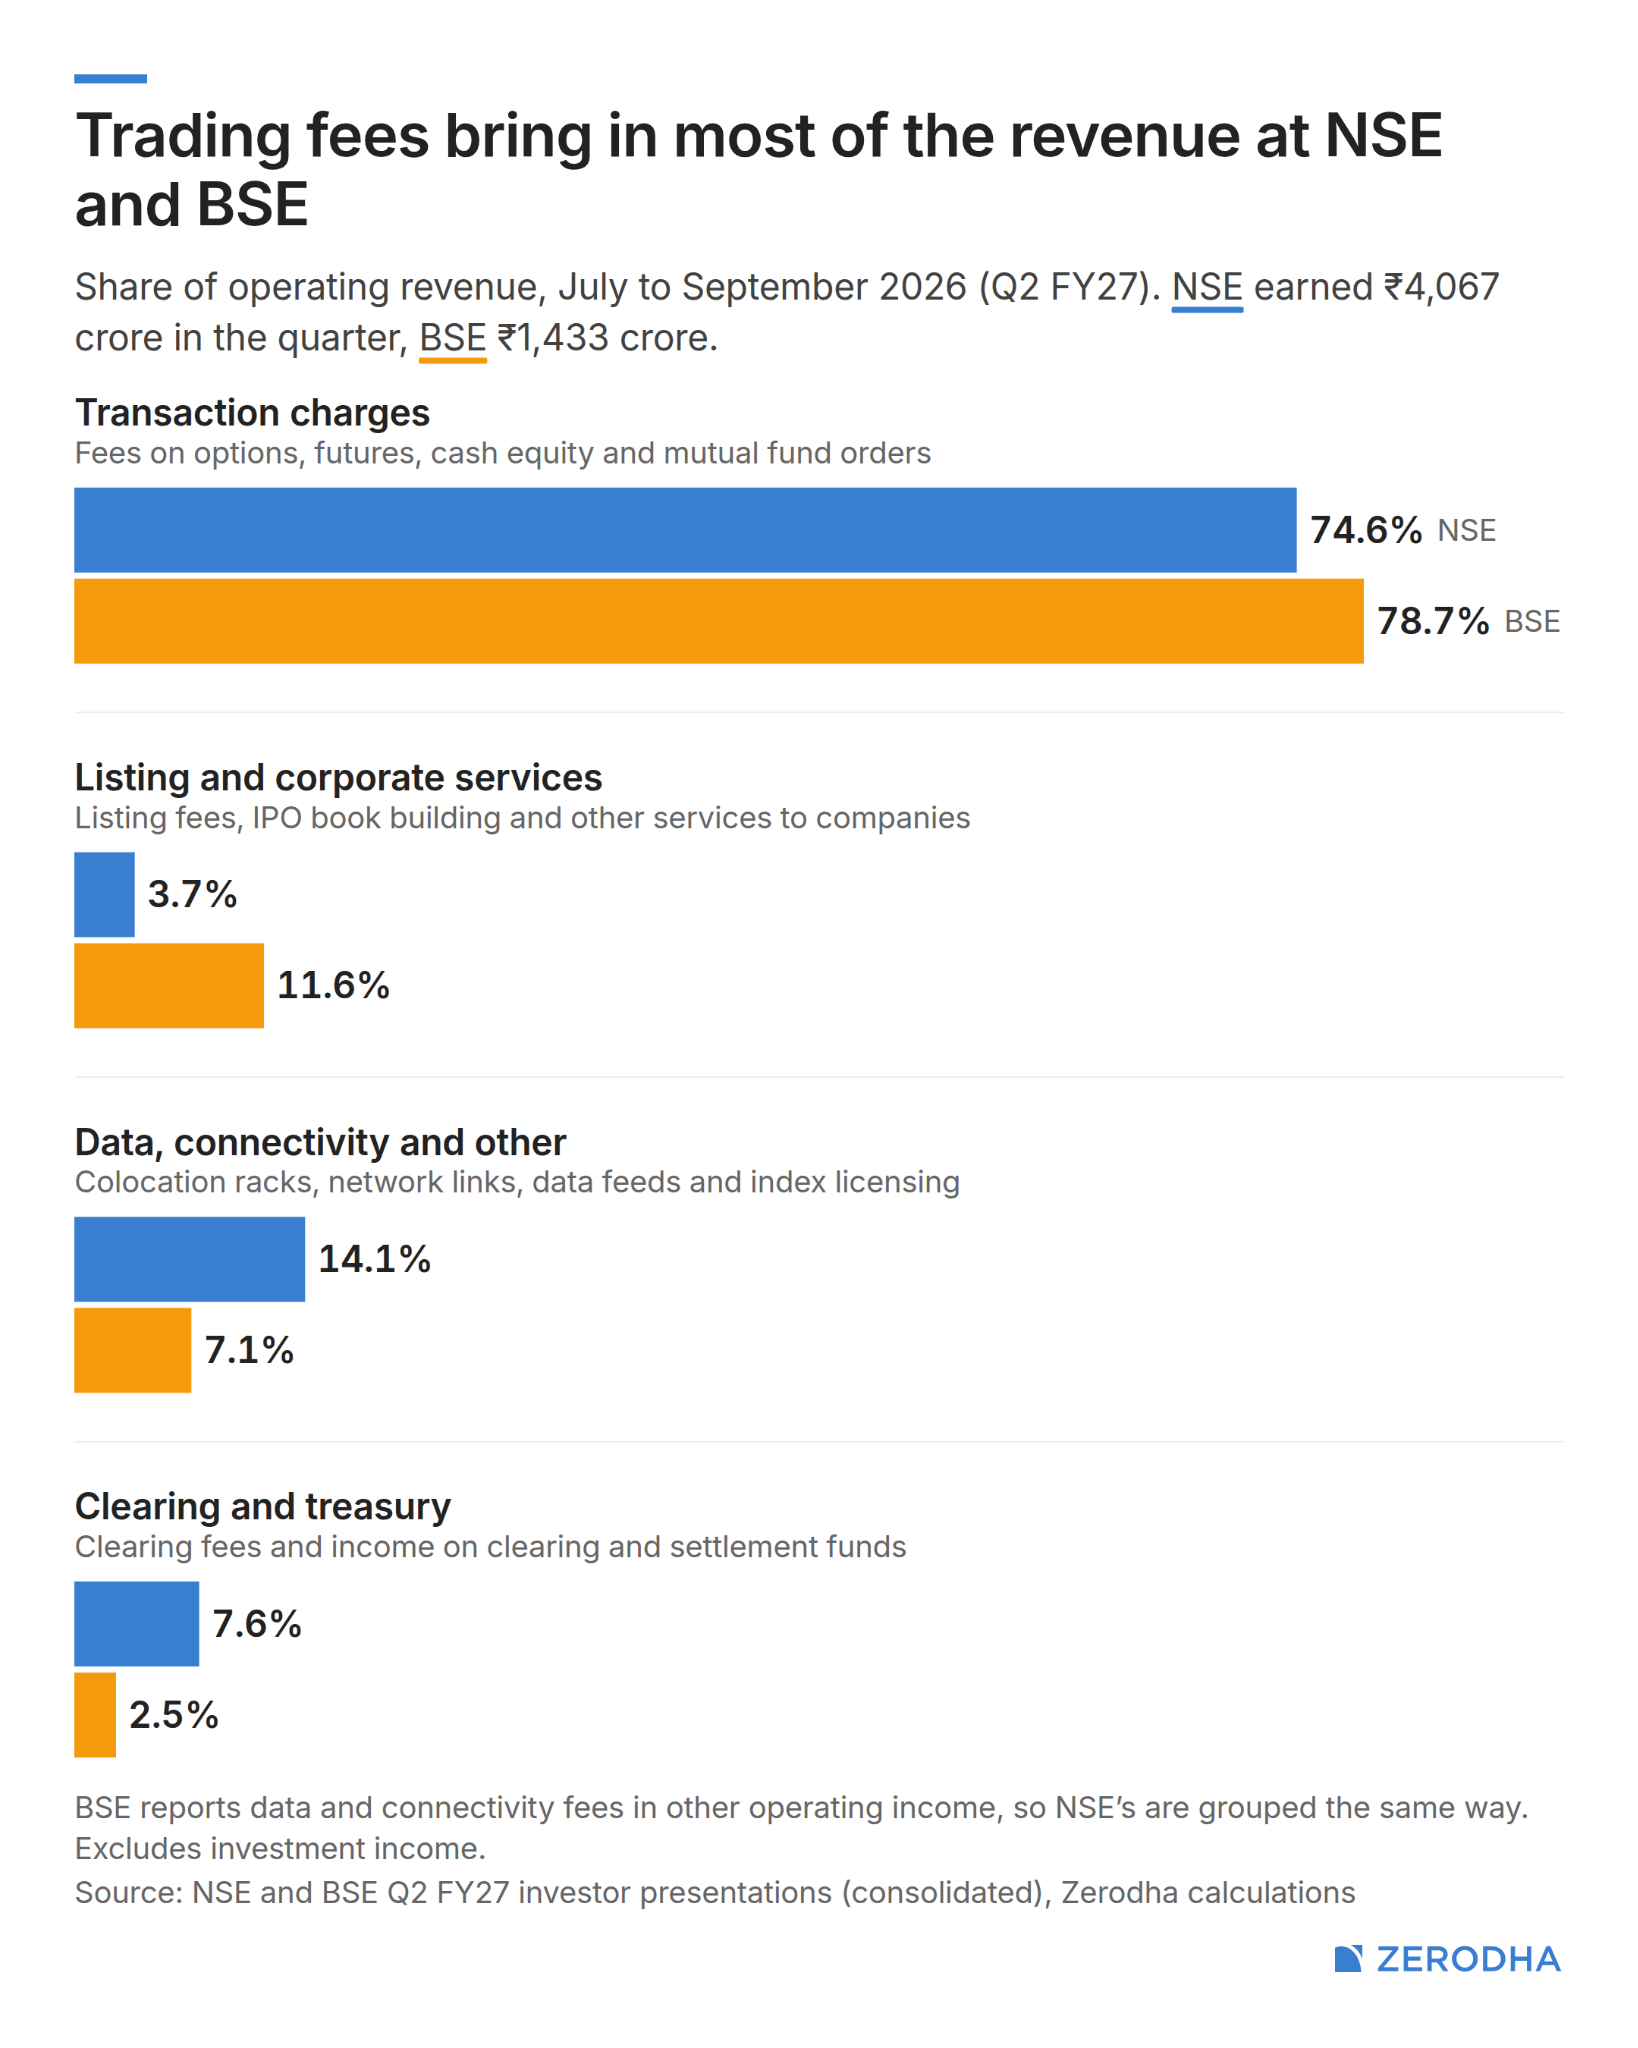
So the July–September quarter is the first time India’s two stock exchanges have reported results side by side. NSE’s revenue from operations came to ₹4,067 crore, and BSE’s to ₹1,433 crore. Both were up from a year ago, NSE by 11% and BSE by 34%, but both slipped from the previous quarter, by 11% and 8.5%.
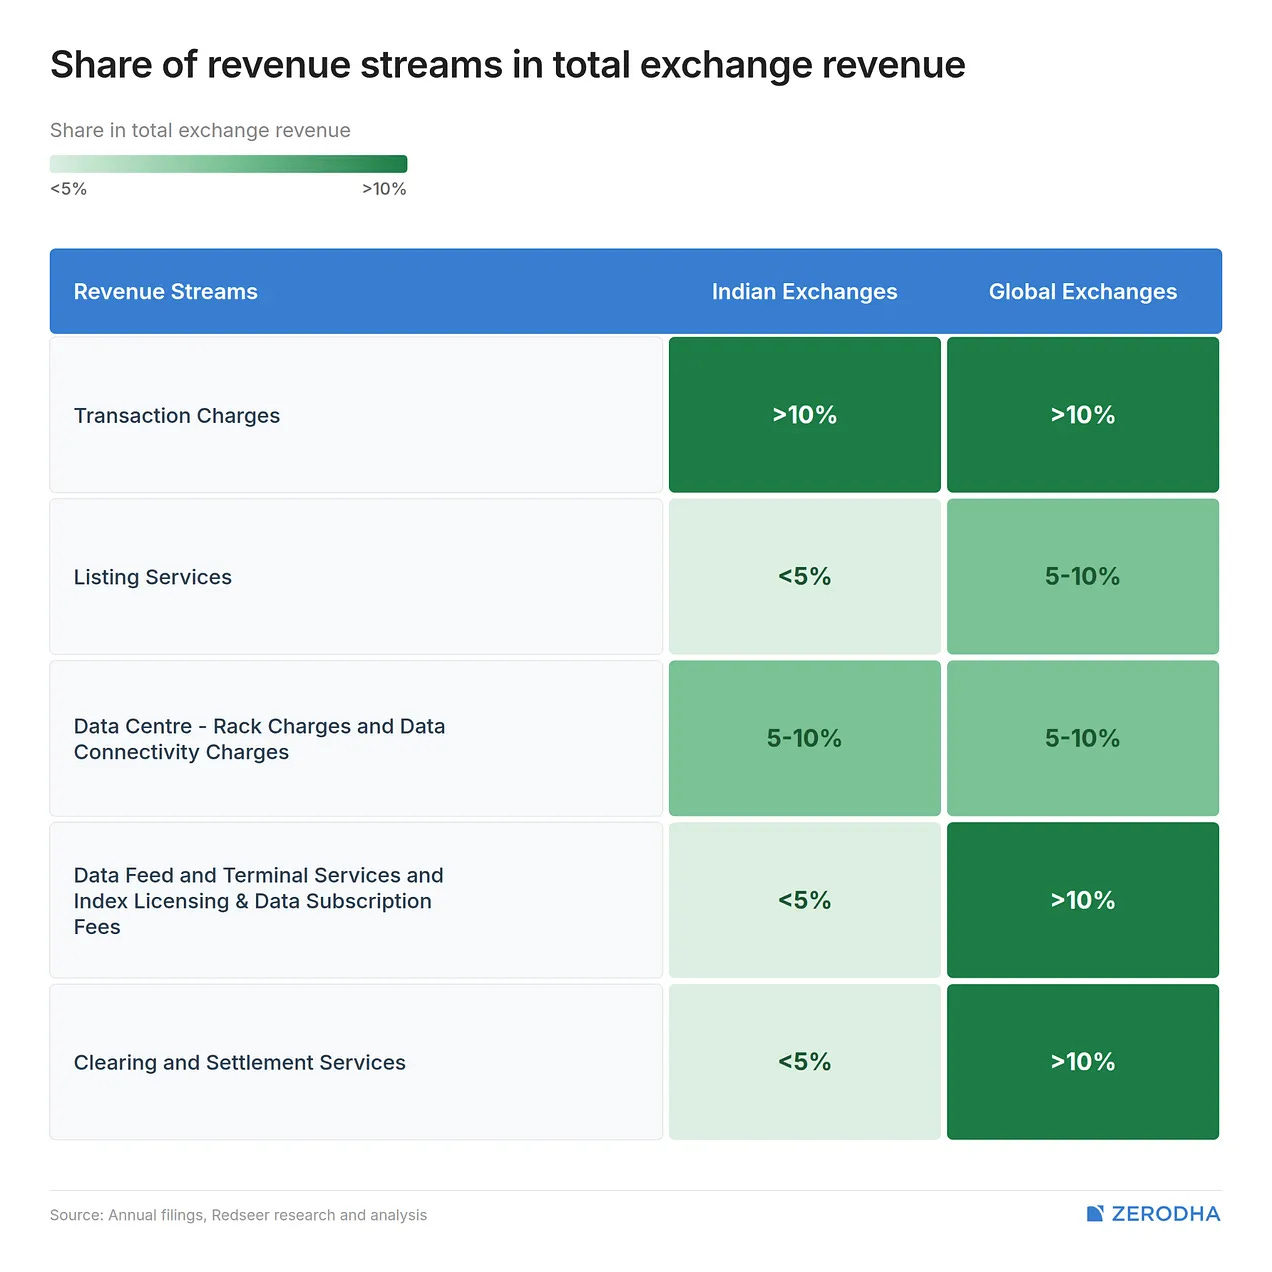
Nearly all of it comes from four places: transaction charges on trades (be it cash, futures, options, or even mutual fund orders), about 75% of NSE’s revenue and 79% of BSE’s; fees from listed companies; charges for market data and for plugging into their systems; and interest on money brokers park with them.
It’s our first look at the two together, so we’ll go slow, walking down their income statements and asking what each says about the market, and the people trading in it.
The month the closing bell broke
Start with a quirk every trader should know. On options, the exchange’s fee is calculated on the premium you pay, not on the size of the position underneath it. Premiums swell when markets get nervous, because protection gets costlier. So an exchange’s biggest revenue line cares a little less about whether markets rise or fall, and more about how jittery they are. Sure enough, NSE’s transaction revenue has closely tracked India VIX, the market’s “fear gauge”.
This quarter, both exchanges took a knock. Transaction charges fell about 15% from the previous quarter, as options trading dropped by roughly a quarter.
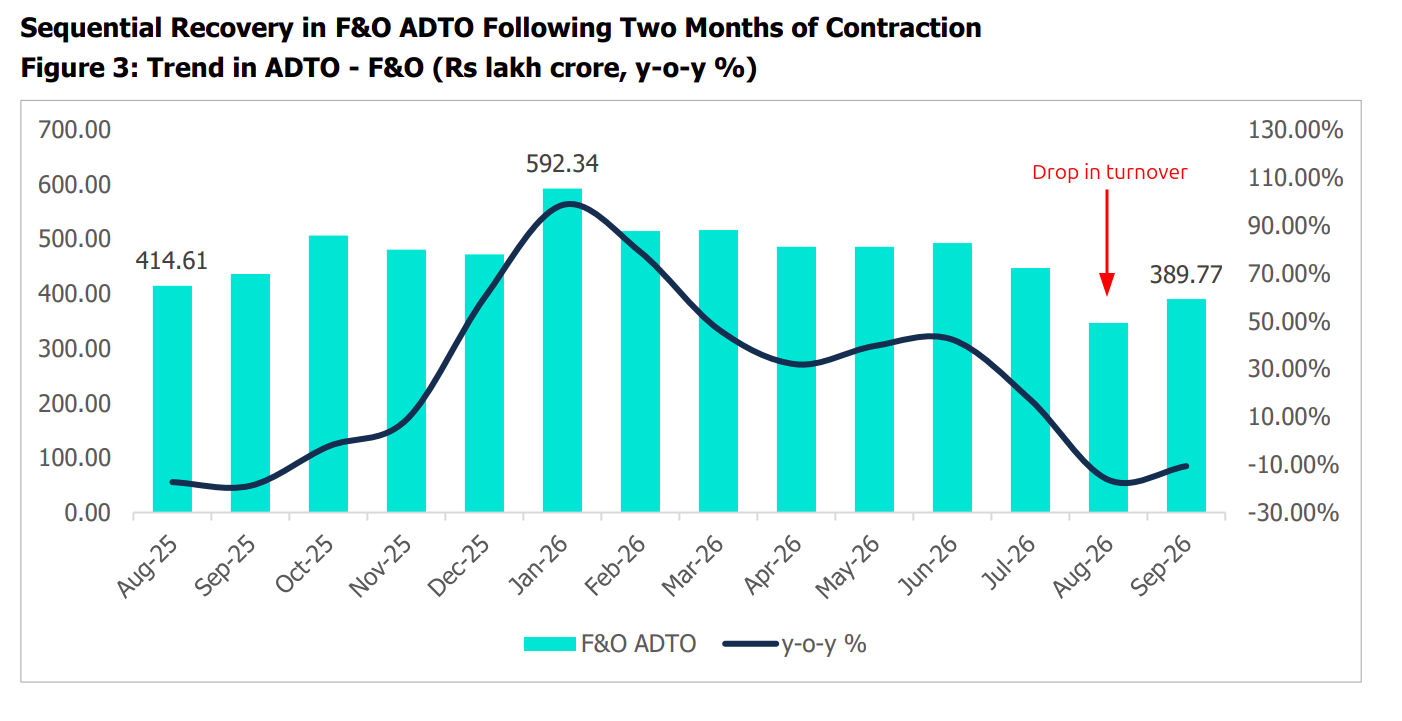
Several things hit at once, and neither exchange could say how much each mattered. The first was simply calm markets: with volatility low, premiums shrank, and BSE’s management blamed “compressed volatility” for the dip. The second was a change to how the market closes. From 3 August, SEBI introduced a Closing Auction Session (CAS) for stocks with futures and options.
Earlier, a stock’s closing price was its average price over the last 30 minutes of trading. Under CAS, continuous trading in these stocks stopped at 3:15 pm, followed by a 20-minute auction that pooled buy and sell orders to discover a single closing price.
This isn’t an exotic idea. The NYSE and the London Stock Exchange use closing auctions too, since much institutional money, especially from passive funds, wants to trade right at the close. But in India, that auction price also became the settlement price for options expiring that day. Whether an expiring option paid off now hinged on a 20-minute auction that could swing sharply, on precisely the day traders least want a surprise. Many simply stepped back.
A couple of days in, as closing prices swung, Nithin Kamath, Zerodha’s CEO, argued that the auction itself wasn’t the problem; it had exposed how shallow our markets are.
India has over 13 crore registered investors, but only about 20–30 lakh trade on a given day. Closing auctions work best with plenty of market makers and arbitrageurs to smooth out prices, and India has far fewer. Shorting in the cash market is hard, because borrowing shares isn’t easy. And thanks to how securities transaction tax (STT) is levied, futures have become a costlier way to trade than options.
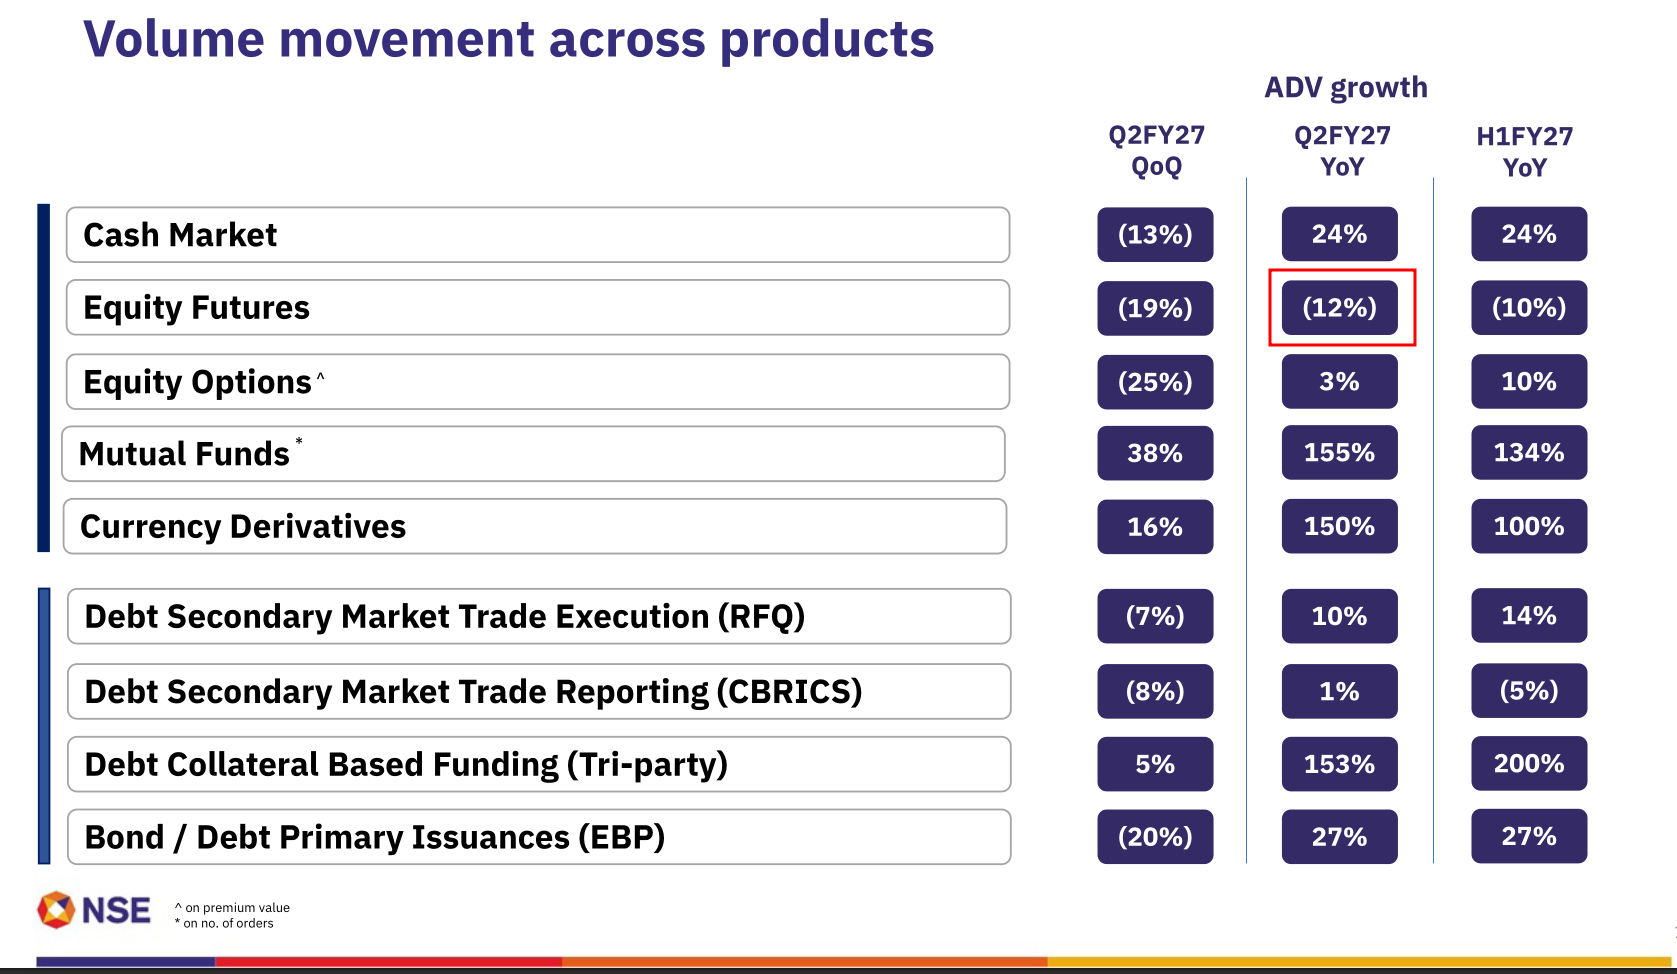
That last point was a headwind of its own. From 1 April, STT on futures went up 2.5 times, charged on the contract’s full value, while on options it rose by half, and only on the premium. The same bet is now often cheaper through options, and NSE’s futures trading fell 12% from a year ago.
Then there was the timing. On 1 July, new RBI rules kicked in that make it harder for brokers to get bank guarantees, which many use instead of cash to put up margins with the exchange. Neither exchange could say how much of the slump came from this. Many brokers had extended their guarantees before the deadline, so the real test may come only as those expire.
The slump didn’t last. Trading picked up in September, and in October, BSE’s options trading hit an all-time high as volatility returned. SEBI, meanwhile, was rethinking its auction. After a consultation in September, it decided on 15 October that from 7 December, expiring contracts would again settle on the last 30 minutes’ average price.
So the rebound came before the fix took effect, and SEBI reworked a market-wide rule barely ten weeks after launching it.
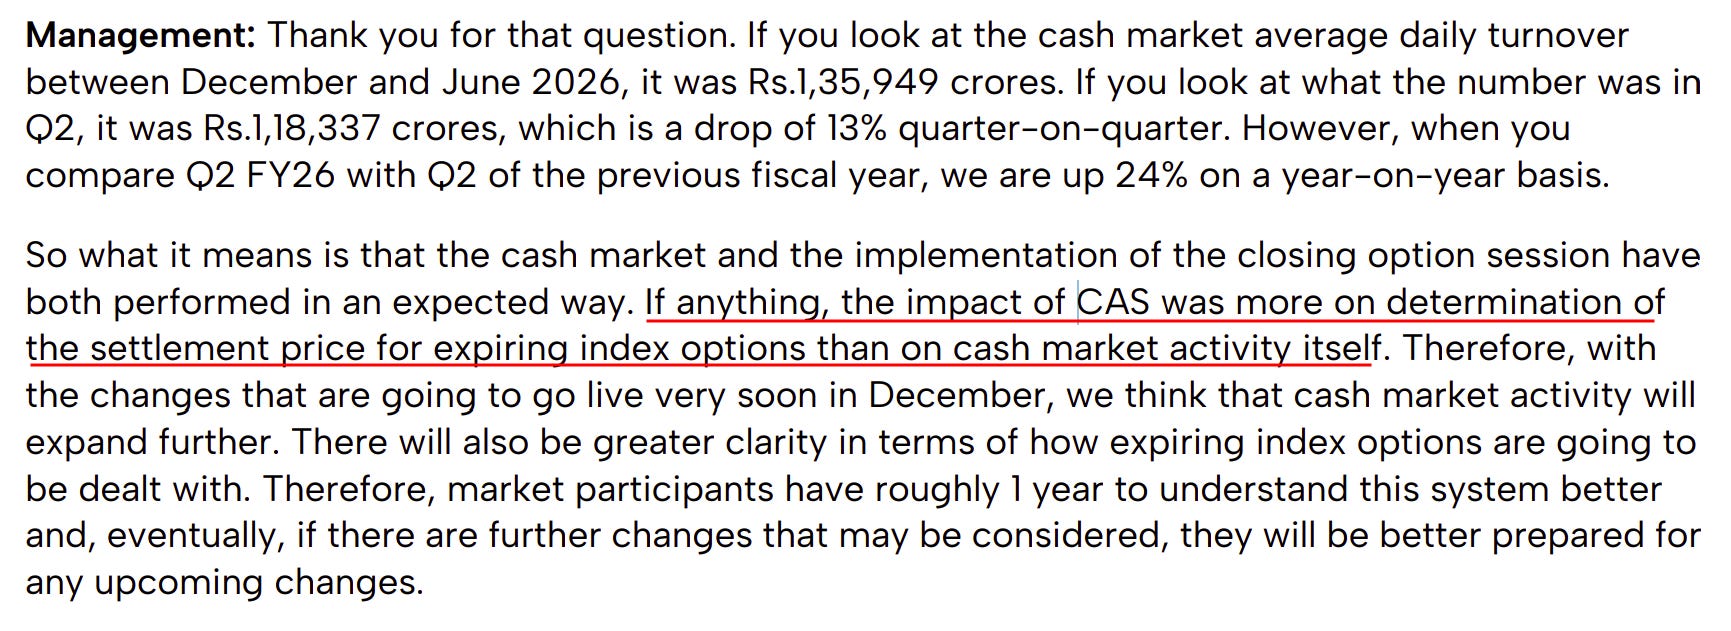
The cash market, where people buy and hold actual shares, fared better. NSE’s average daily cash turnover fell 13% from the previous quarter, but was 24% higher than a year ago; NSE’s management said CAS hurt expiring options far more than ordinary cash trading.
And people kept borrowing to buy stocks: the margin trading book hit a record ₹1.56 lakh crore in September. Those are cash-market purchases, so borrowed money helps keep shares changing hands, and each of those trades earns the exchanges a cash transaction fee.
Same market, two very different businesses
Put the two exchanges’ trading businesses side by side, and they barely look like the same kind of company.
NSE is, for practical purposes, a monopoly. It handles about 92% of the cash market and practically all futures, and management says it has close to 100% of monthly index options and single-stock options. It has lost ground in just one corner: weekly index options, where BSE has clawed back a real share since 2023.
The big tension is that this contested corner is also NSE’s biggest earner. Weekly Nifty options brought in 42% of NSE’s revenue from operations. That’s down from 48% the quarter before, but barely changed from 43% a year ago, so NSE isn’t diversifying as fast as that drop suggests. Its cash market charges, though, grew a healthy 30%.
BSE is a different animal. Its average daily options premium rose 50% from a year ago, against NSE’s 3%, and it holds about 36% of index options by premium. By notional value of contracts traded, though, it’s almost as big as NSE.
The gap exists because BSE is essentially an expiry-day exchange. About 77% of its options volume comes from contracts expiring that day or the next. Options that are about to expire are cheap, since there’s little time left for the market to move. So for every ₹100 worth of contracts traded on BSE, traders paid only about 12 paise in premium; on NSE, about 23 paise.
That’s why BSE looks big when you count contract value, but smaller when you count premium, which is what its fees are charged on. Outside expiry weeks, its share drops to about 6–7%, and in monthly contracts, to about 2%.
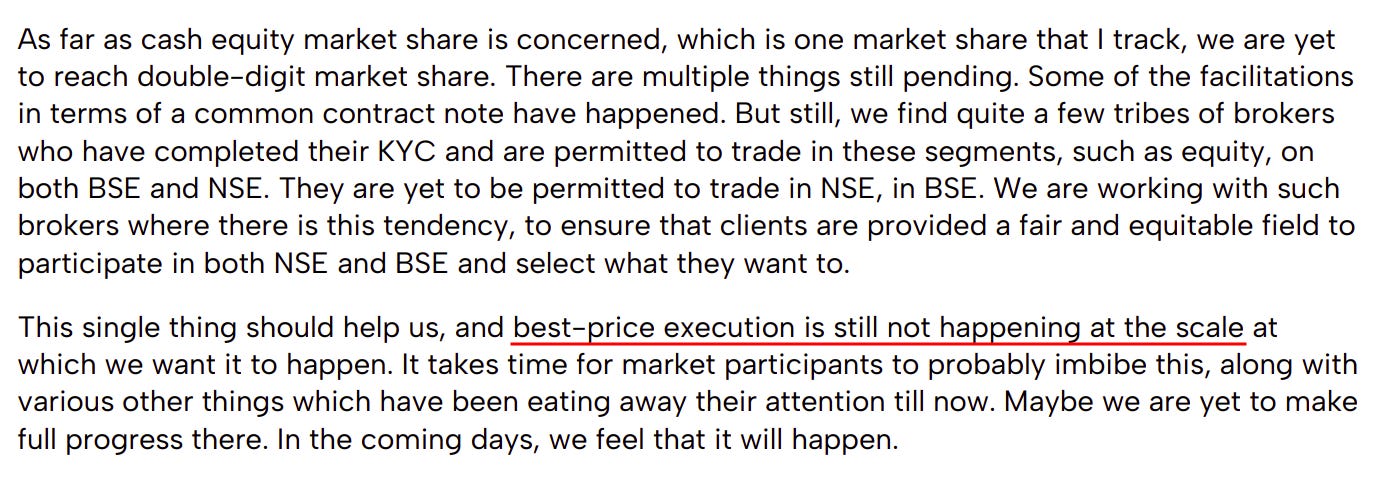
BSE has been chipping away at the cash market too. Its cash turnover grew even as NSE’s fell, lifting its share to 8.1% from 6.8%. It wants double digits by early 2027. What’s holding it back, BSE says, isn’t the product. Many brokers have done the paperwork for clients to trade on both exchanges but still don’t let them trade on BSE. And “best-price execution”, which automatically routes your order to whichever exchange offers a better price, isn’t happening at scale.
BSE is also cheap. Its futures transaction charges are close to nil, some equity derivatives charges are below NSE’s, and in August, it said its co-location order-flow charges were about 20% of market rates. That may change: this quarter, it said it will raise transaction, co-location and rack charges at the appropriate time, based on market feedback. It gave no timeline.
In short: NSE is a near-monopoly whose single biggest earner sits in the one market it has to share, while BSE is a cheaper, expiry-day challenger that’s bigger by volume than by revenue, and has room to charge more.
A record IPO season, and what it’s actually worth
If trading had a rough quarter, the primary market had a spectacular one. September saw over 30 mainboard listings, India’s most ever in a month. BSE counted 71 mainboard IPOs in the first half, a record for any half-year.
This shows up as listing revenue, the fees companies pay to list and stay listed. NSE’s rose 70% from a year ago, and BSE’s 20%.
But in absolute terms, it’s tiny. NSE’s ₹150 crore of listing revenue is under 4% of its total, about what weekly Nifty options earn it in five or six trading days. For an exchange, a listing’s real value isn’t the fee, but the years of trading the stock brings.
The smaller lines, where the long game is
The rest of the revenue is small, but it’s where both exchanges are building a future less tied to daily options trading.
Take market data. When we looked at NSE’s IPO, we saw how global exchanges earn a big chunk of revenue from selling data. Indian ones don’t: BSE’s presentation pegs data at 4–5% of revenue in India, against 10–25% in developed markets. NSE’s data feed and terminal revenue grew 43% from a year ago to ₹165 crore. Yet NSE plans to give away Market Lens, a new investor data tool, for free.
BSE is going the other way: from 1 January, it ends its 13-year partnership with Deutsche Börse, which marketed its data overseas, and will sell to global clients directly.
Then there’s co-location: racks inside an exchange’s data centre where trading firms place their servers, so their orders arrive microseconds faster. NSE has about 1,870 member racks and room to spare. BSE’s 500 are all taken, so it’s building more.
A quieter contest is playing out in mutual fund platforms, which distributors and apps use to place fund orders. BSE’s StAR MF is the giant here, but NSE’s share of orders jumped from 12% to 22% in a year.
The most striking growth is in commodities. NSE’s commodity options trading grew tenfold between January and October, mostly in crude oil, after it moved crude options’ expiry earlier and allowed co-location. On 8 October alone, options covering over a billion barrels of crude changed hands.
NSE’s fees are just a twentieth to a fiftieth of those charged by MCX, the incumbent. Yet commodities are still too small to get their own line in NSE’s revenue breakdown.
Both exchanges are also placing smaller bets. NSE has launched Electronic Gold Receipts, which turn physical gold into tradable units, set up a coal exchange subsidiary, hosted India’s first tokenised bond issues for REC and L&T, and awaits RBI approval for corporate bond index futures. BSE has partnered with MSCI on index-linked derivatives, pending regulatory approval. None move the needle yet.
Why BSE’s margin rose in a bad quarter
So far, we’ve looked at what the exchanges earn. What they spend is just as revealing, and it starts with a puzzle. BSE’s revenue fell 8.5% from the previous quarter, yet its operating margin rose, to about 68%, its highest ever.
The answer lies in its costs. About half go on two items, regulatory fees paid to SEBI and clearing and settlement charges, both of which move with trading volumes. When volumes dropped, so did they. This shock absorber is why management calls 65–70% margins sustainable.
The regulatory fee hides a curious detail. SEBI charges exchanges on total trading turnover, not revenue, and BSE’s notional options turnover is nearly as large as NSE’s. So this quarter, BSE paid ₹166 crore in regulatory fees and NSE ₹171 crore: practically the same, though NSE earns almost three times BSE’s revenue.
NSE’s costs work differently. Only about 18% move with volumes. The biggest chunk, roughly a third, is technology, up 22% from a year ago, and NSE expects it to keep growing in the mid-teens. Some of it goes to AI, which NSE runs entirely in-house, without public AI models, since most of its data is private.
Employee costs rose 18%, mostly due to new labour codes. With costs that don’t shrink when trading does, NSE’s operating margin slipped to 76% from 78% the previous quarter, though it was flat from a year ago.
You may also see headlines saying NSE’s expenses fell 51% from a year ago. That’s because a year ago, it set aside ₹1,297 crore to settle long-running SEBI cases; strip that out, and expenses rose 10%.
Profit, and the float underneath it
All of this flows to profit. NSE earned ₹2,578 crore after tax, up 23% from a year ago, though much of that is last year’s settlement charge falling away; adjusted for one-offs, pre-tax profit grew 9%. BSE’s profit rose 45% to ₹809 crore.
One last line reveals what an exchange quietly is: a large pool of money earning interest. NSE holds more than ₹50,000 crore in treasury investments, about two-thirds its own money and the rest margin money and settlement funds that brokers keep with it. This quarter, NSE earned ₹479 crore from these investments, about 14% of its pre-tax profit. That was 30% less than the quarter before, a big reason its profit fell faster than its revenue. BSE saw a smaller dip.
The takeaway: an exchange earns not just when people trade, but also on the money that sits with it while they do.

Carlsberg India’s IPO rests on one strong beer
If you had a beer in Maharashtra or Rajasthan last year, there’s roughly a one-in-three chance it was made by Carlsberg India. And most of what Carlsberg India sells is just one beer: Tuborg Strong.
Carlsberg India, the Indian arm of the Danish brewer, is now going public. It filed its draft prospectus on October 27, for an IPO that could raise up to ₹6,660 crores.
We’ve written about India’s alcohol market recently, mostly through listed companies. This DRHP lets us go a layer deeper, into how a brewer in India actually makes money, how much of it Carlsberg keeps, and what exactly is on sale. Let’s start with the market it sells into.
How much does India love beer?
India is the world’s third-largest alcohol market, but beer makes up only about a third of the alcohol Indians drink by volume. And the average Indian adult, over 21 years of age, drinks about 3.5 litres of beer a year, compared to 30L in China and 75L in Brazil in FY 2026.
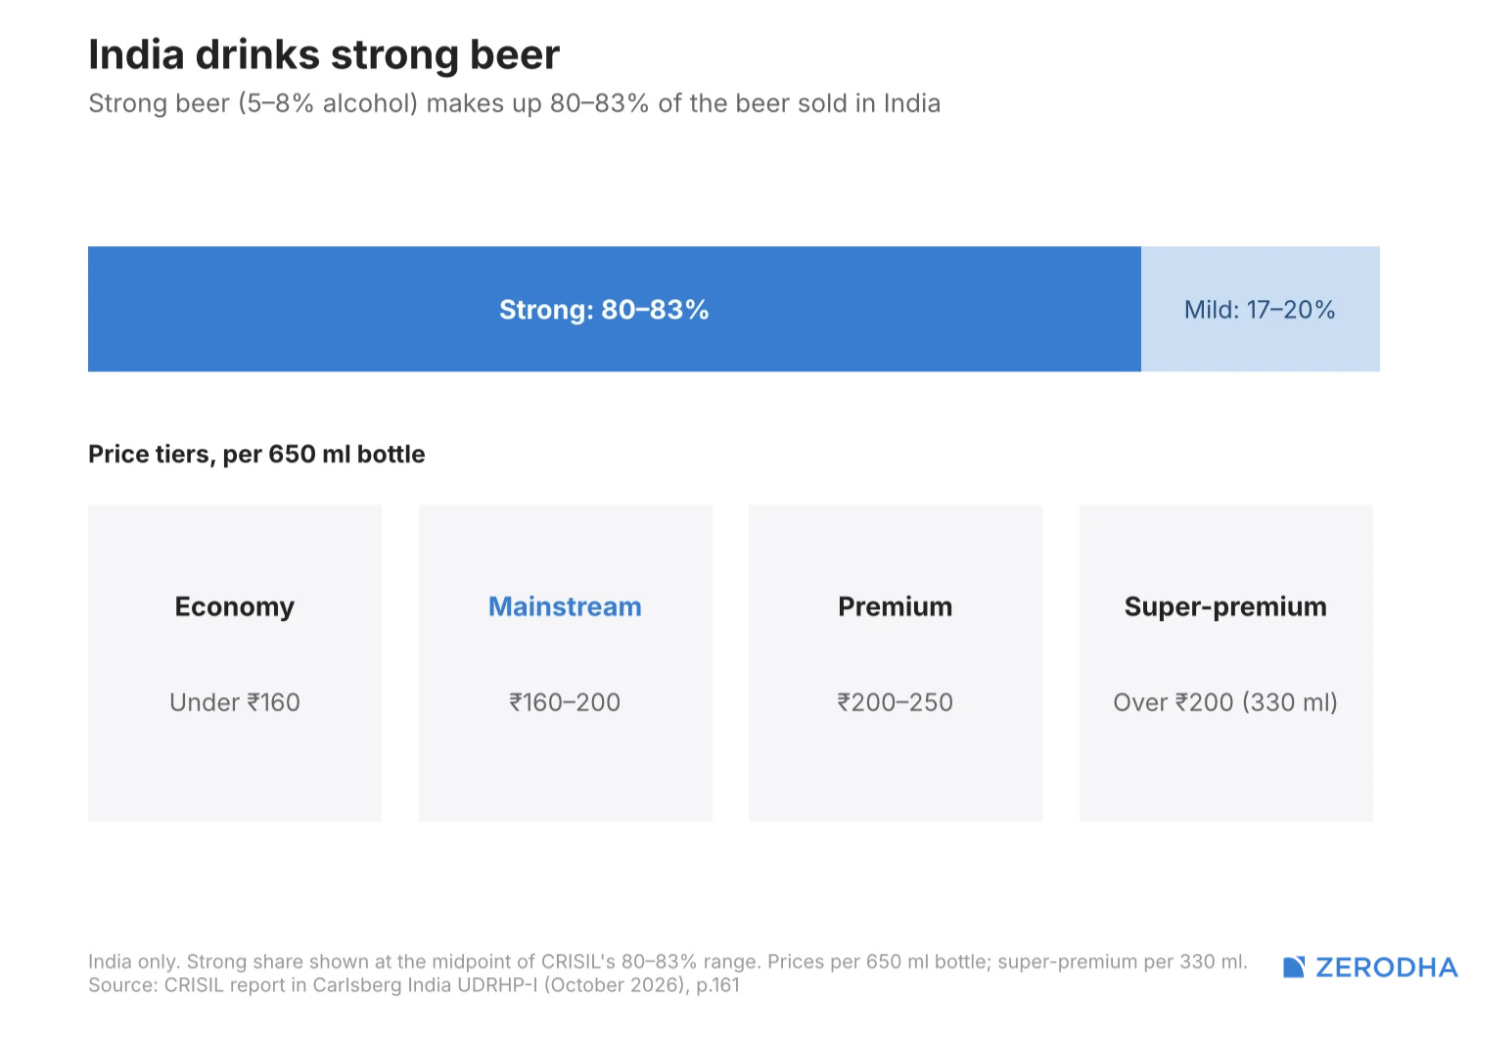
Beer in India comes in two kinds: Strong beer has 5-8% alcohol by volume (ABV), while mild beer has under 5%. Strong beer makes up 80% of all beers sold in India.
The beer market has also grown slowly, at only 3.1% a year, between FY20 and FY26, though CRISIL projects that growth will pick up to 6-7% a year until FY30.
And within this, Carlsberg India has poured itself a sizable share of the market.
What does Carlsberg India actually do?
Carlsberg India is the country’s second-largest brewer. It holds about 22% of the market across 16 key states, which together account for three quarters of India’s beer volume.
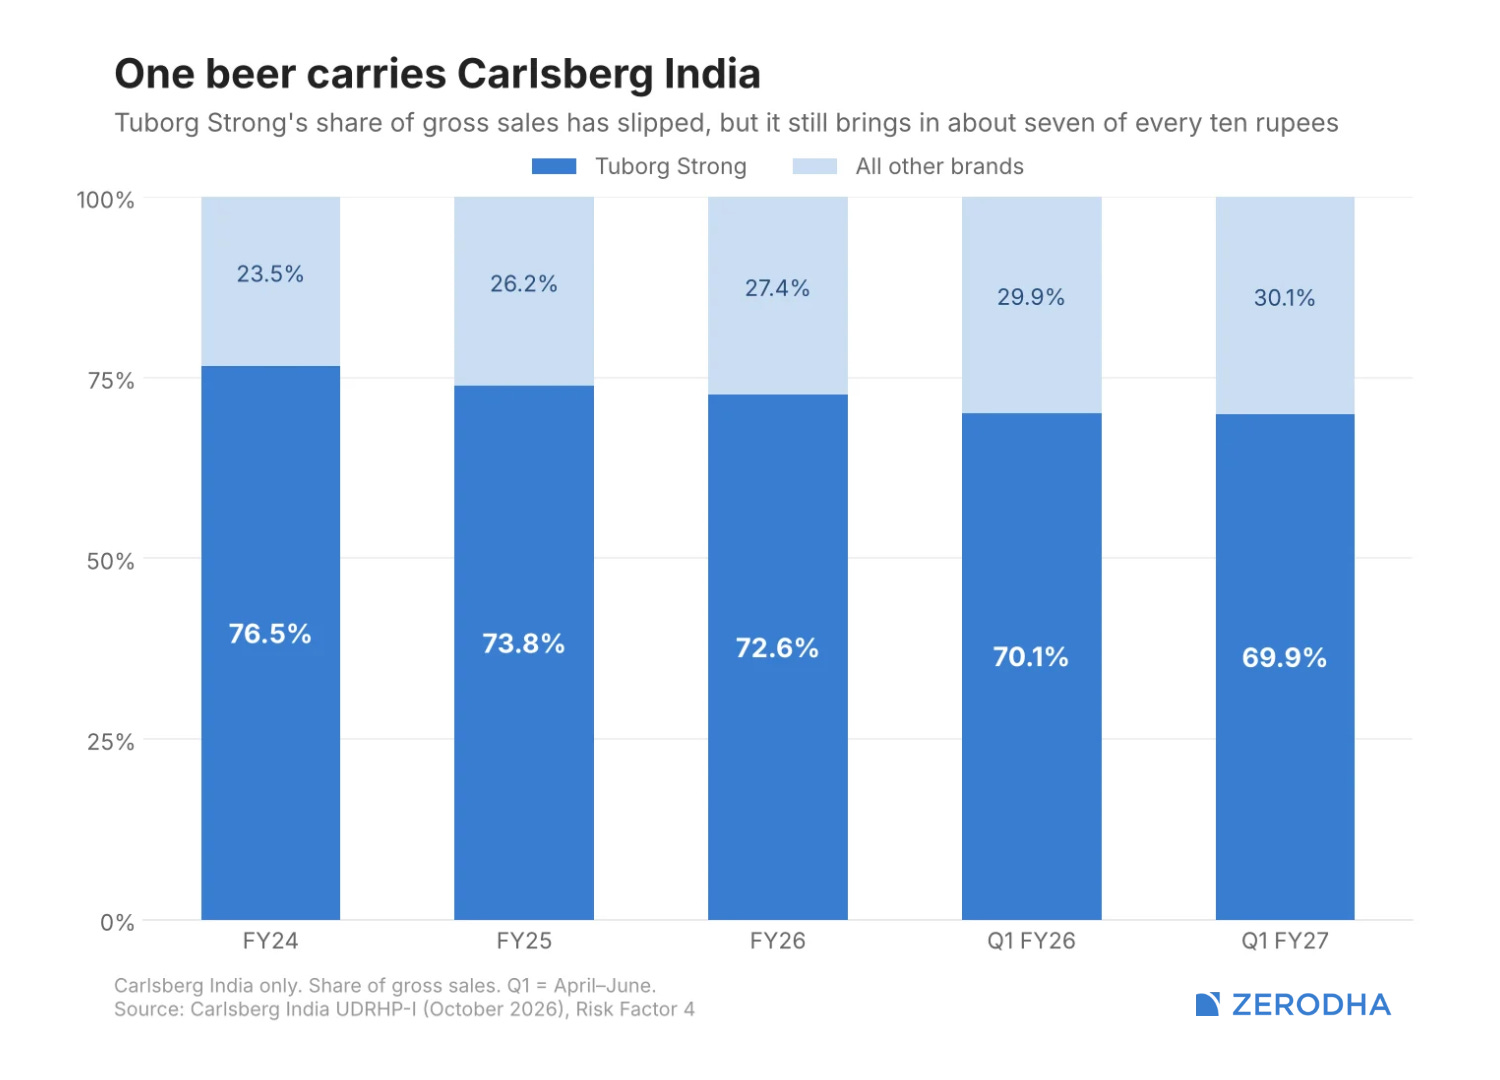
What surprised us most is how much of that business comes from one beer: Tuborg Strong, a mainstream strong lager, which brought in 72.6% of the company’s gross sales in FY26. That share has slipped from 76.5% in FY24, while other premium brands like Carlsberg Elephant and the French wheat beer 1664 Blanc have grown.
Now, that concentration might be risky to some. But remember that strong beer is ~80% of the market, and that’s exactly where Carlsberg has placed its bet.
So, how is all this beer made? Two ways: Carlsberg India owns seven breweries, and it also pays nine external brewers, called co-manufacturers, to add more capacity. And its own breweries are running close to full capacity while the contract brewers made 42% of total volume in FY26, up from 31% in FY24. New breweries are planned, which the company says are needed to meet growing demand.
Making enough beer is a challenge, but getting it to customers is another, and in India, that part works a little differently. We wrote about this recently: running an alcohol business in India can feel like running 28 different businesses, because every state has its own rules.
In most businesses, a company chooses its distributors. For Carlsberg India, a few states such as Karnataka, Rajasthan and Odisha are the primary wholesale distributors via state-owned beverage corporations. And these state-owned corporations finally sell it to alcohol shops in a few states. About 40% of Carlsberg India’s volume moved this way in FY26.
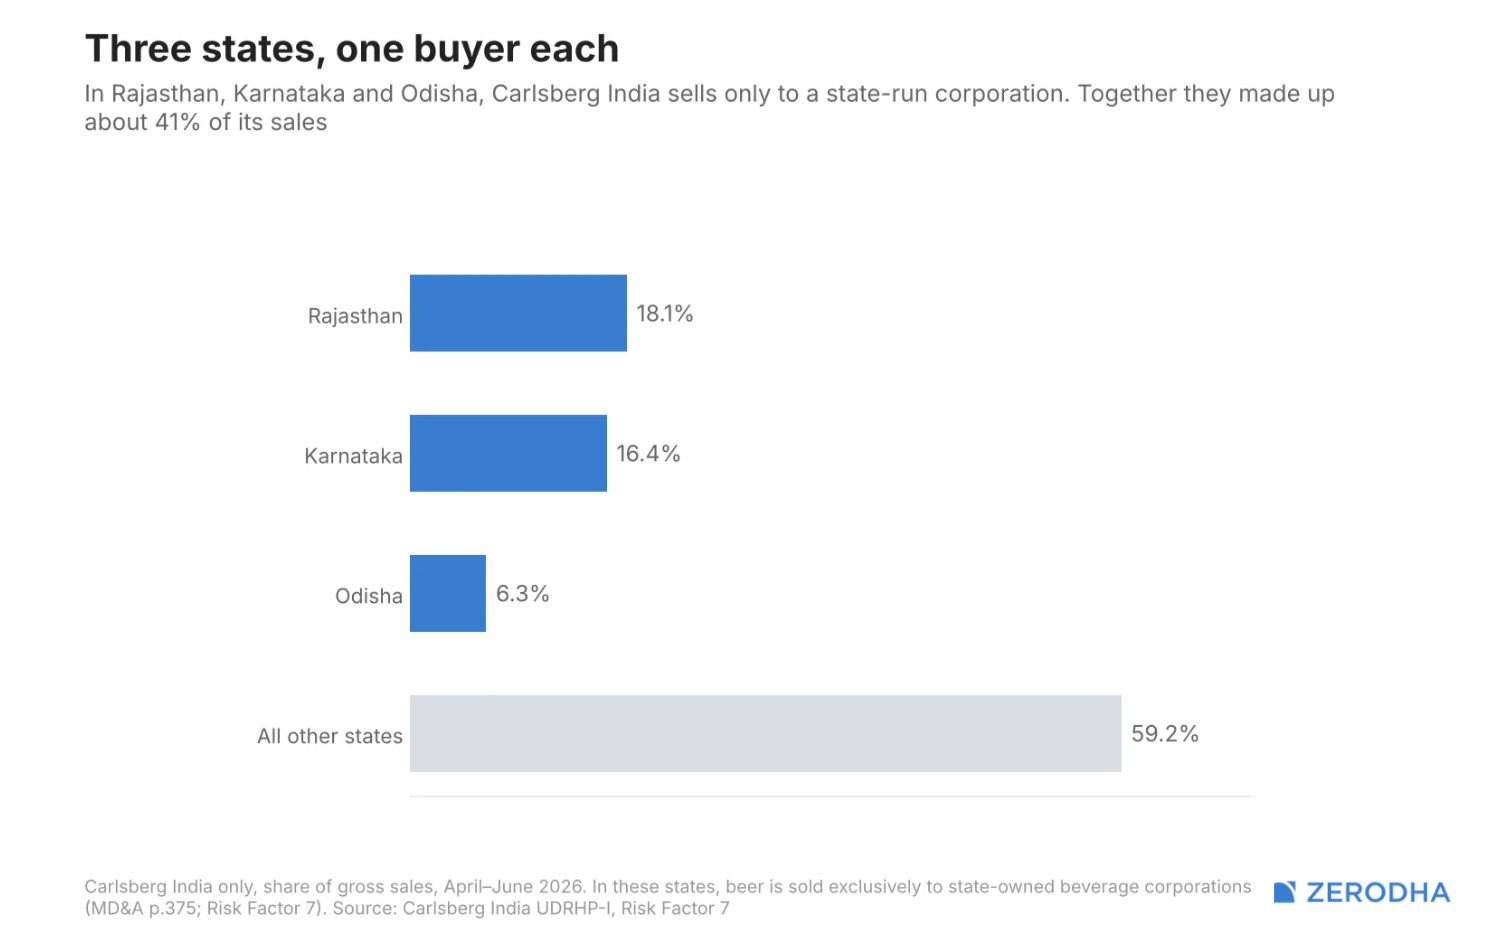
The DRHP counts state-owned corporations among its key customers, and singles out those in Karnataka and Rajasthan as buyers whose business it depends on. In other states, like Maharashtra, it sells through private distributors instead.
Both these models bring risks: State corporations pay late, with one corporation owing Carlsberg India ₹85 crore in overdue bills in June 2026. For instance, Carlsberg’s rival, United Breweries temporarily halted its Kingfisher beer supplies in early 2025 due to a pricing dispute with the Telangana state-owned corporations. The private model, meanwhile, comes with fragmented middlemen and, as the DRHP warns, informal retailer cartels.
How does Carlsberg India make (beer) money?
Before diving into Carlsberg’s numbers, you first need to understand two fees it pays before it earns anything: Excise to the state government, and royalty to its parent company.
Excise is the tax a state charges on alcohol. Carlsberg collects it as part of its price and hands it over to the state. Because it passes through Carlsberg’s invoices, accounting rules count it as revenue, even though Carlsberg never keeps a rupee of it.
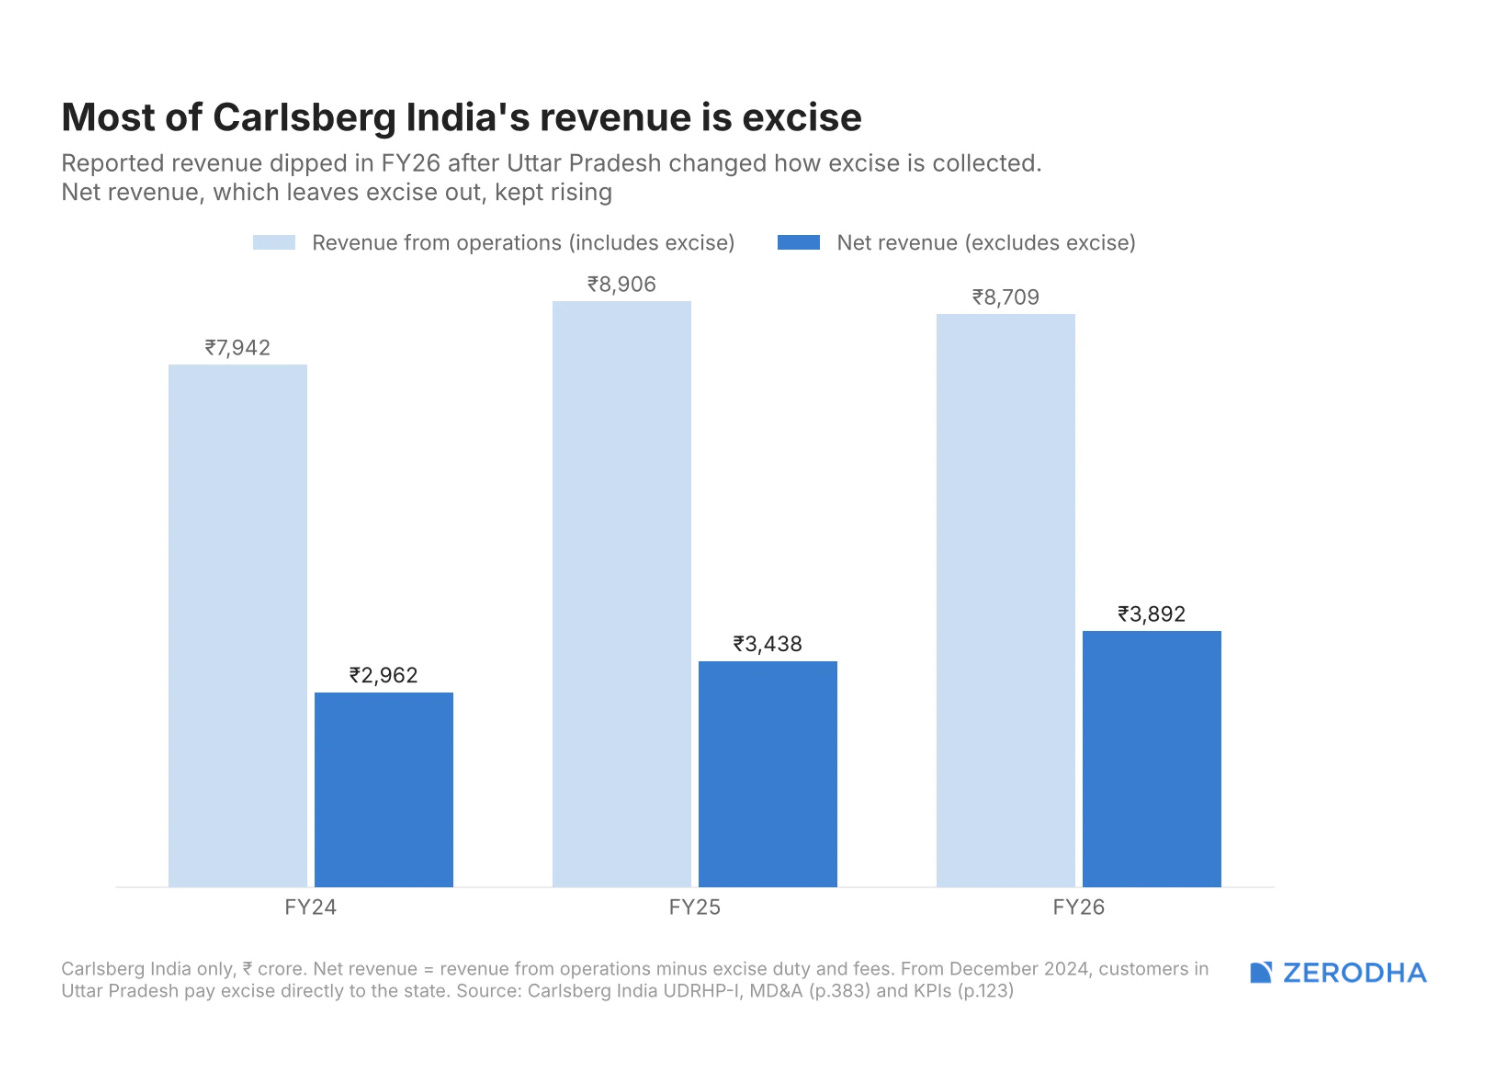
And excise is huge: In FY26, Carlsberg India reported revenue of ~₹8,700 crore, and 55% of it was excise. So, the company tracks net revenue, which is revenue minus excise. That came to ~₹3,900 crore.
The second fee, royalty, is far smaller but it does say a lot about who really owns the brand. To sell a beer with the brand name ‘Tuborg’, Carlsberg India pays a fee to the parent company, much like a franchise. In FY26, royalties came to ₹90 crore, or 2.3% of net revenue. The licence runs for five years, and if it isn’t renewed, the company can’t sell these brands at all.
So, how does this weigh in Carlsberg India’s revenue? Carlsberg India’s reported revenue fell 2.2% in FY26, and some reports described that as a decline.
But the company says this was mainly because Uttar Pradesh changed its rules: customers there now pay excise to the state directly, so that tax no longer passes through Carlsberg’s books. Net revenue, which leaves excise out, actually grew 13.2%.
Measured by net revenue, Carlsberg’s Indian business has been growing faster than its market for a long time. Between FY14 and FY26, its volumes grew 11.8% a year, against 5% for the industry. More recently, between FY24 and FY26, net revenue grew 14.6% a year, which the company attributes mainly to gaining market share. Premium and super-premium beers also rose from 21.3% to 24.7% of net revenue over that time.
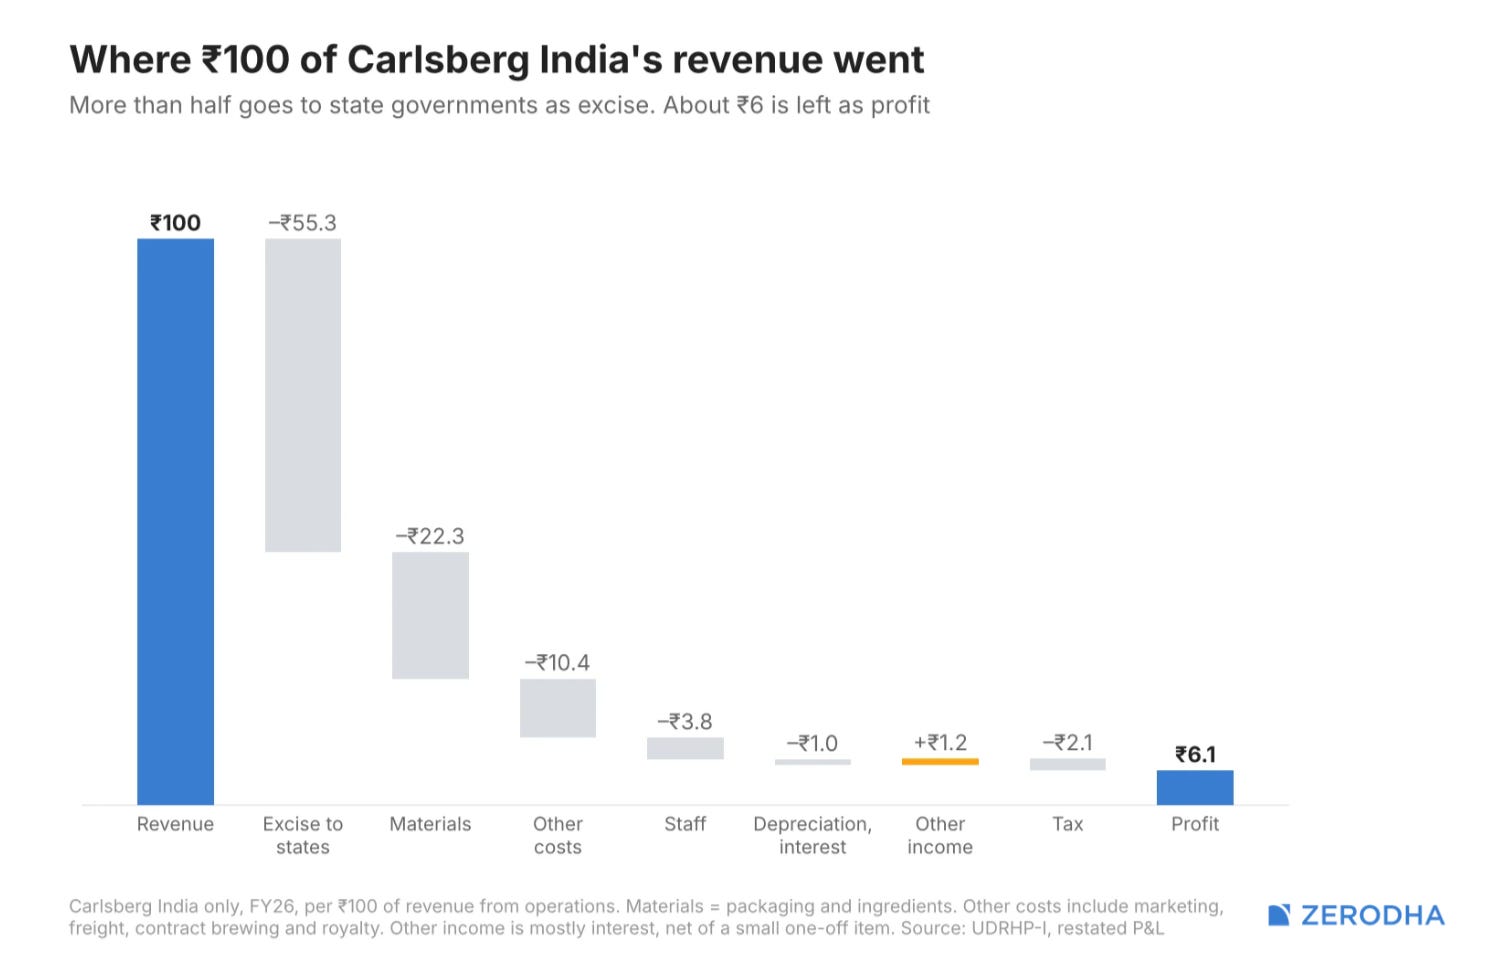
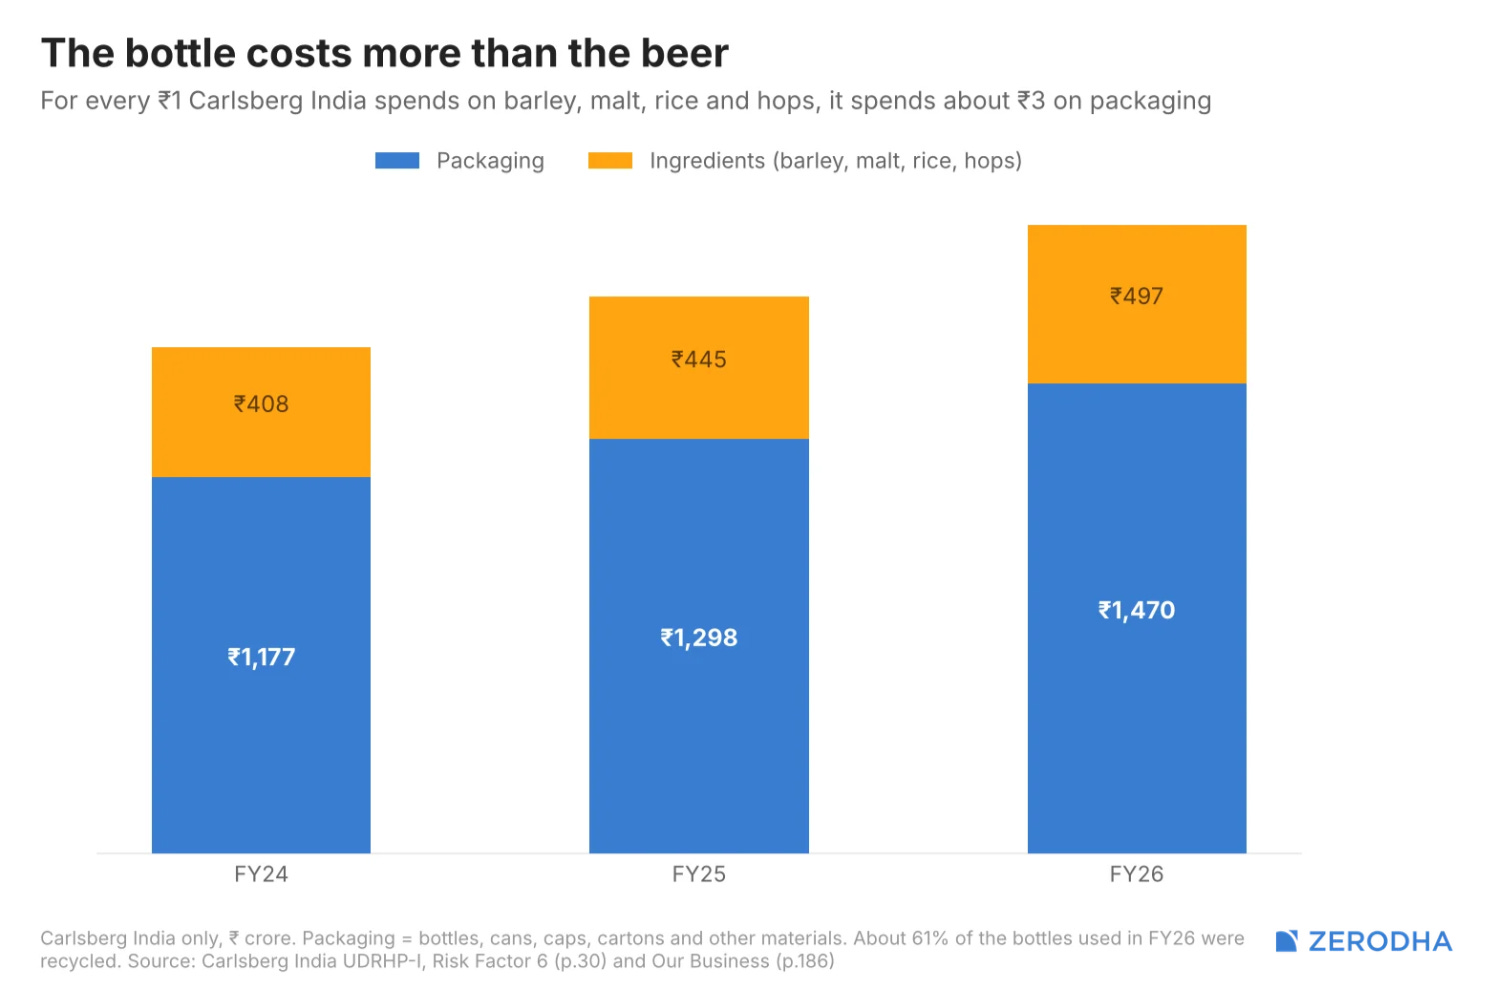
After the state takes its share in excise, the next big cost is materials. In FY26, Carlsberg India spent ₹1,470 crore on packaging (bottles, cans, caps etc.) against ₹497 crore on raw materials like barley. It’s also partly why the company recycles 61% of its bottles in FY26.
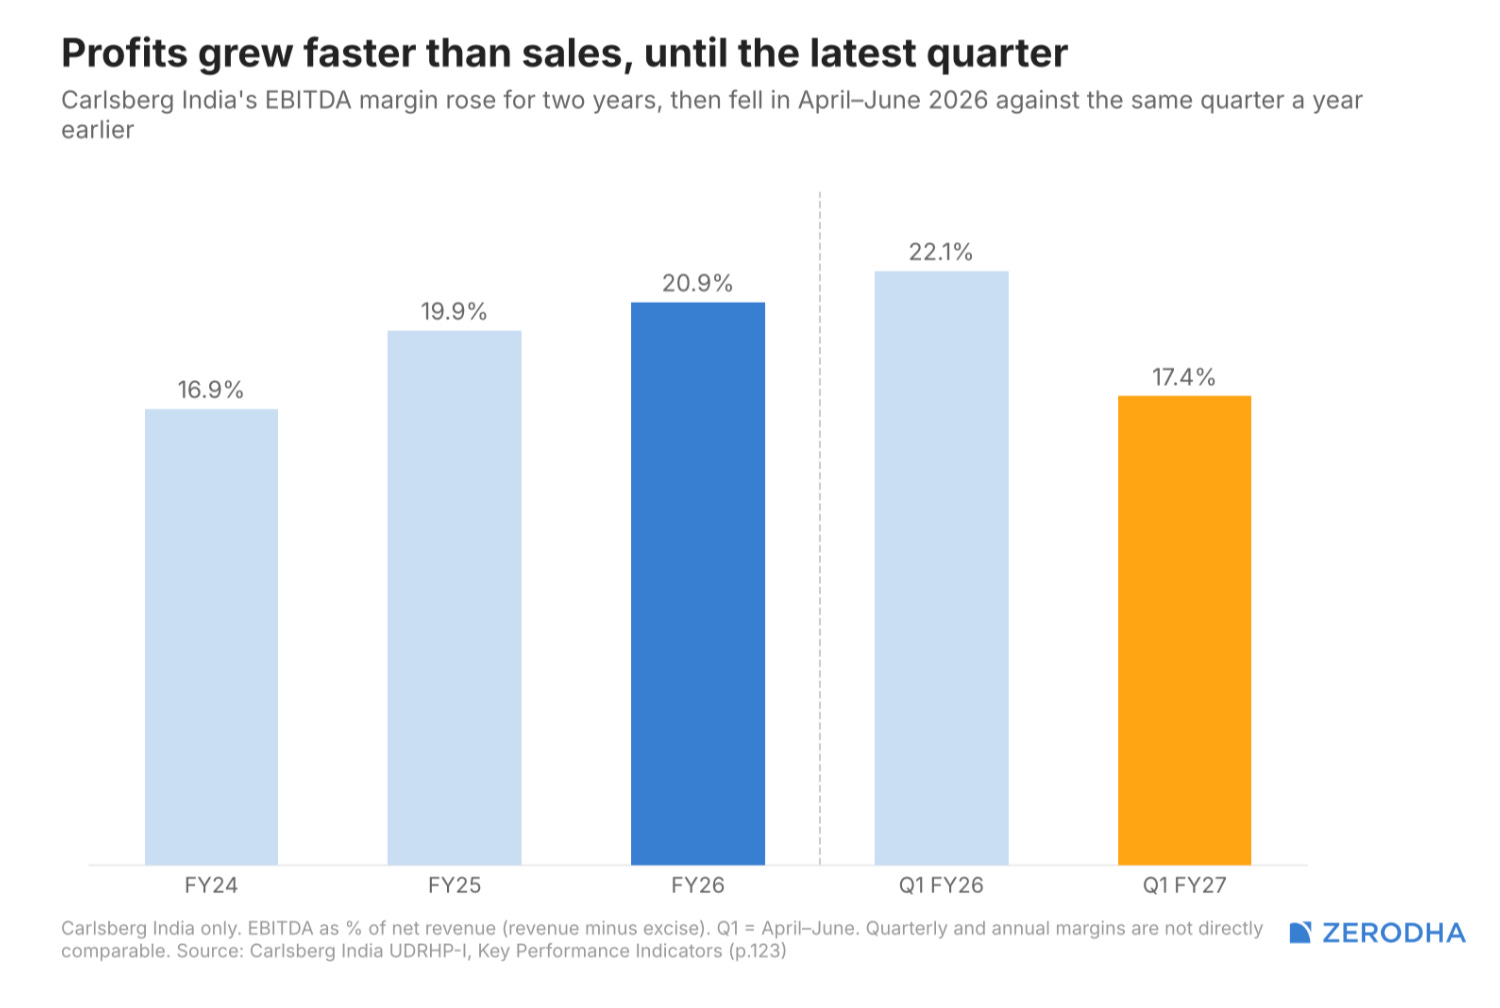
What’s left at the end has been growing. Profit after tax rose from ₹321 crore in FY24 to ₹535 crore in FY26. Over the same period, EBITDA margins rose from 16.9% to 20.9% of net revenue. The company had no borrowings as of June 2026, and about ₹1,750 crore in cash.
The latest quarter broke that run. In April-June 2026, net revenue grew 21%, but profit fell ~4%, and the EBITDA margin dropped from 22% to 17%.
Costs rose on several fronts at once. Spending on marketing and promotions went up 76%. A shortage of aluminium cans linked to the Iran war meant paying more for alternative supply. And since states have to approve beer prices, Carlsberg couldn’t pass costs overnight.
By its own numbers, then, Carlsberg India is growing and profitable. How does that compare with its biggest rival?
What are others brewing?
United Breweries, the maker of Kingfisher and part of Heineken, sold about three times as much beer in FY26. Yet, it made less profit at ₹413 crore, against Carlsberg India’s ₹535 crore in FY26.
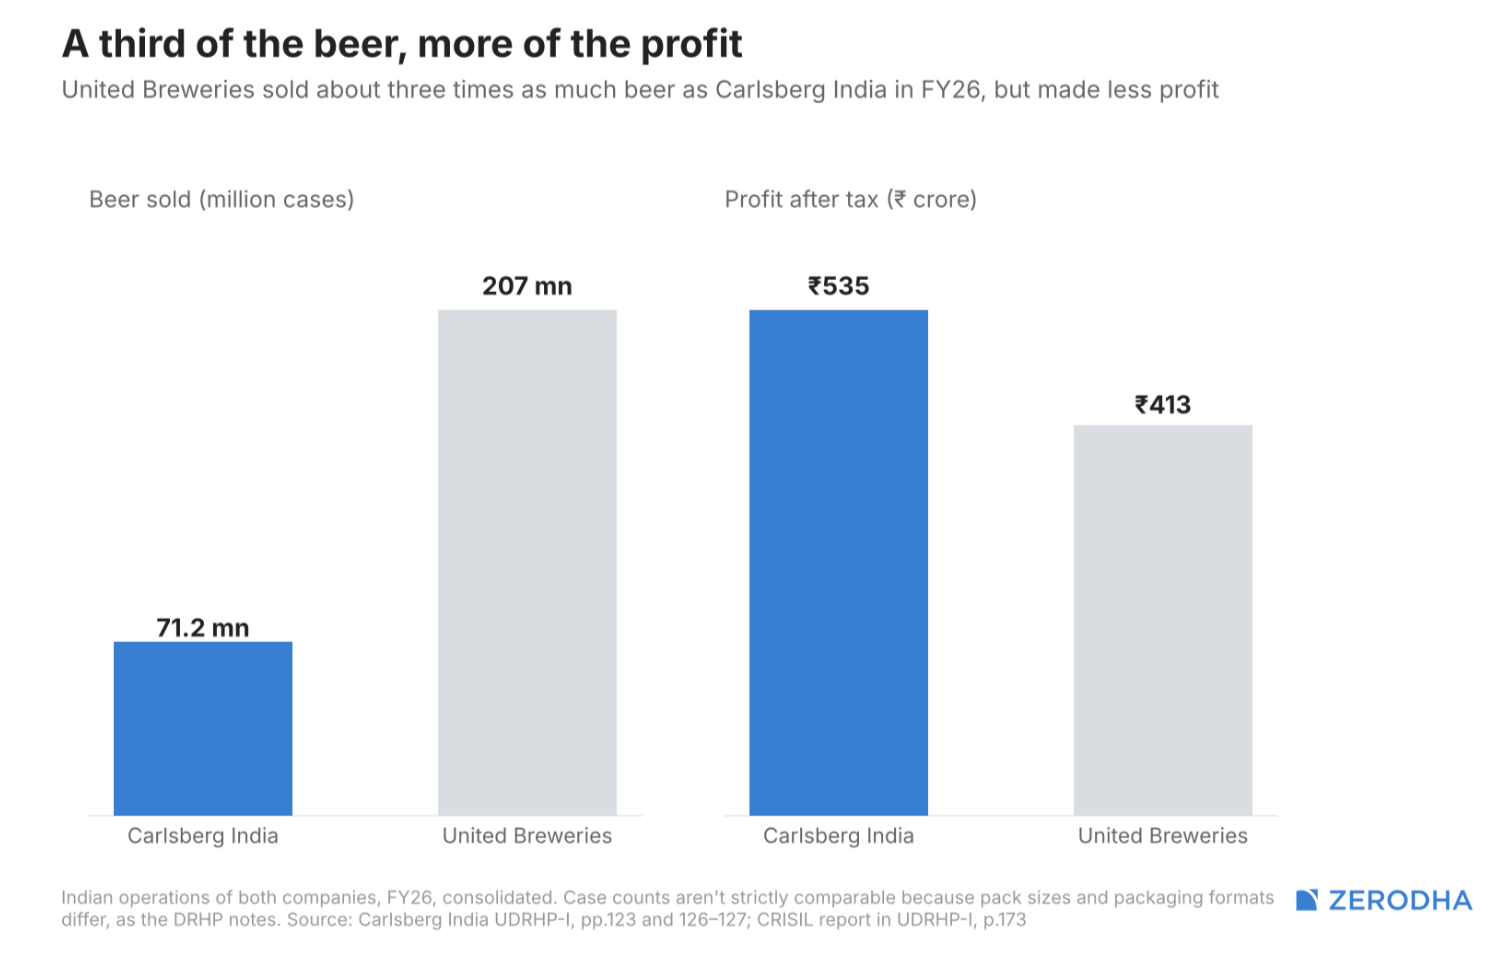
Part of that gap is timing. FY26 was a rough year for United Breweries, which it blamed partly on unusually heavy rains. It has since bounced back: in July–September 2026, its volumes grew 16% and its net revenue 24%.
But the gap is also structural, and it starts at the gross margin, which is what’s left after paying for materials. Carlsberg India kept 50% of its net revenue in FY26, against 44% for United Breweries. The gap widens further down. Carlsberg’s EBITDA margin was 20.9%, more than double United Breweries’ 9.2%.
Part of that gap comes down to where the two companies sell. United Breweries’ management in October explained it had yet to win price increases in states that account for nearly 30% of its business, including Telangana and Andhra Pradesh. Carlsberg India, meanwhile, had a relatively small presence in both states.
So why list now, and who gets the money?
As the DRHP states, Carlsberg India, the Indian arm, itself won’t receive any money from this IPO, as It’s entirely an offer for sale:. South Asian Breweries, the parent’s Singapore holding company, is selling up to 15% of the company, so the money goes to the parent.
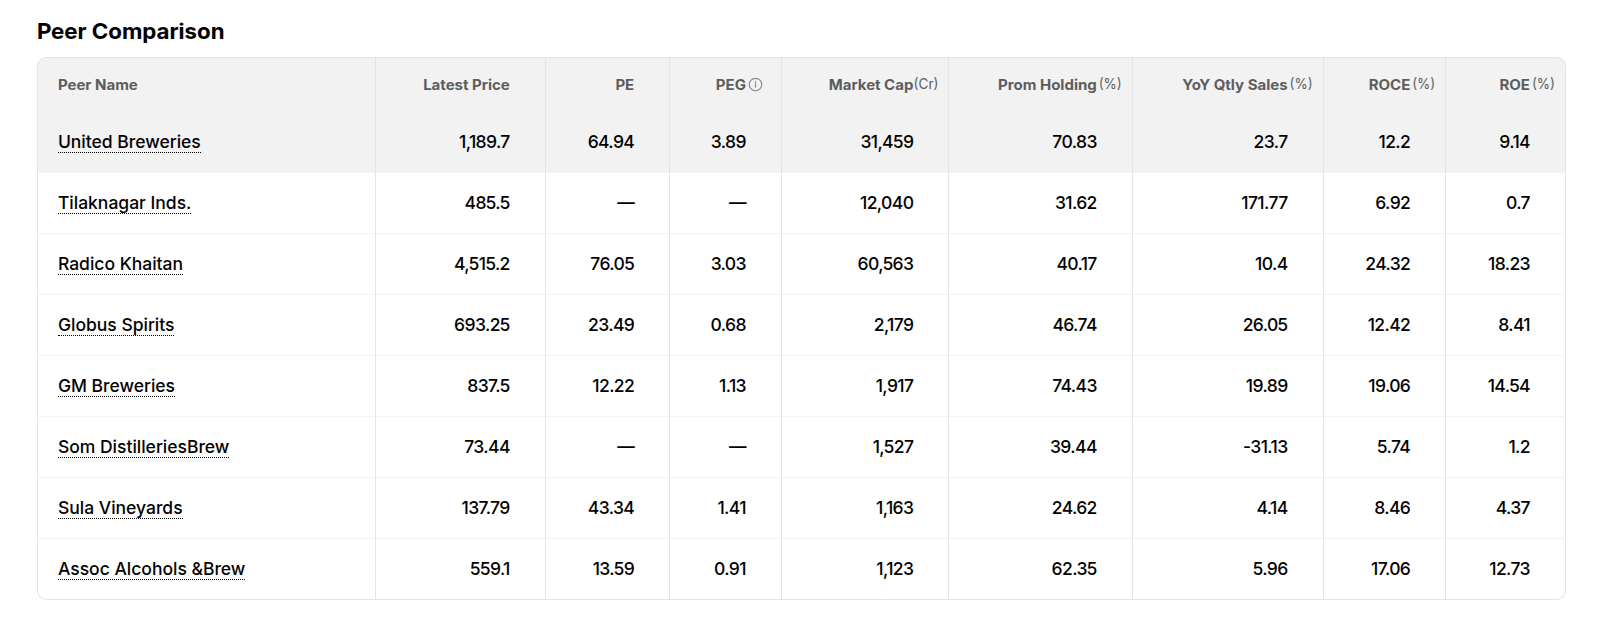
In early 2026, Carlsberg Group CEO Jacob Aarup-Andersen stated it was “purely driven by whether it created value for Carlsberg’s shareholders”. And it comes down to valuation, since listed alcohol companies in India trade at 40-80x their yearly earnings.
And Carlsberg isn’t alone in noticing. Pernod Ricard is preparing a potential Indian listing, and Coca-Cola is exploring one for its Indian bottling business.
The Bottom(s up) line
When we last looked at India’s alcohol companies recently in June 2025, we argued that the higher you climb up the price ladder, the more stable things seem to get. Carlsberg India complicates that, as its profits rest on a mainstream strong beer that sells in the middle of the price ladder.
And the DRHP also lists what could go wrong, including demand towards low- and no-alcohol drinks, and a few risks that stand out beyond the ones we’ve already met. One of them is in Rajasthan, the company’s second-largest state by sales. On October 1, 2026, the state’s pollution control board revoked the Alwar brewery’s permission to operate, over alleged emission breaches that the company disputes. Separately, its Haryana brewery was flagged in a national inspection drive, though no action has been taken there yet.
The supply chain is concentrated too. About 70% of its purchases come from just ten suppliers, and the contract brewers that make over 40% of its beer bring risks of their own. One in Odisha was suspended for about two months in FY26 after scoring poorly on quality checks.
Then there’s the parent. The brands, the royalty rate and the permission to build new breweries all stay with it, and it will still own about 85% after the IPO. It can raise the royalty in future, and that rate below a SEBI threshold wouldn’t need minority shareholders’ approval.
And yet, through all that complexity, one strong beer has become big enough to carry most of the company.
- This edition of the newsletter was written by Kashish & Zarieus
Tidbits
1. NCLT declares Videocon promoter Venugopal Dhoot bankrupt over ₹12,668 crore SBI dues
The National Company Law Tribunal(NCLT) has officially declared former Videocon Industries promoter Venugopal Dhoot bankrupt to recover over ₹12,668 crore owed to the State Bank of India. The proceedings, which follow SBI’s invocation of Dhoot’s personal guarantees in 2018, include the appointment of a Bankruptcy Trustee to manage the process and submit a preliminary report within 90 days.
Source: Business Standard
2. DGTR recommends two-year quantitative restrictions on soda ash imports
The Directorate General of Trade Remedies has recommended quantitative restrictions on soda ash imports for two years to protect domestic manufacturers from pricing pressure. The proposed quotas are about 7.55 lakh tonnes in the first year and 7.93 lakh tonnes in the second, but the recommendation still needs government approval.
Source: Financial Express
3. Indian Oil plans to purchase crude and LPG vessels to reduce shipping risks
Indian Oil Corporation plans to acquire its own crude oil and liquefied petroleum gas vessels to reduce logistics costs and manage exposure to rising shipping risks in West Asia. The state-run refiner, which has secured board approval and issued tenders for the acquisitions, currently relies on a time-chartered fleet that has provided substantial savings amid rising freight rates and war-risk insurance premiums.
Source: NDTV Profit
4. SEBI’s revised settlement regulations take effect with online application portal
The Securities and Exchange Board of India’s revised settlement regulations went live on November 7, introducing a dedicated online portal for filing applications, calculating amounts, and accessing support. The updated framework establishes application fees of ₹25,000 for individuals and ₹35,000 for others, sets minimum settlement thresholds, and introduces a fast-track processing mechanism for eligible cases under ₹10 lakh.
Source: Business Today
5. Anthropic buys $3.4 billion worth of gas-fired generators for data centres
Anthropic has agreed to pay about $3.4 billion for commitments to 1.7 gigawatts of gas-fired generators for its data centres, according to the Financial Times. The deal is the largest known single purchase of power-generation equipment by an AI company and gives Anthropic more direct control over the infrastructure powering its computing needs.
Source: Reuters
Want more tidbits? Catch up on last week’s recap!

Beyond Today’s Brief
There’s always more happening at Markets by Zerodha.
The Chatter: How is Bajaj Finserv navigating distribution fee reforms while deploying ₹4,700 crore in surplus cash into new ventures? Why is Bharat Electronics 99% confident of bagging the massive QRSAM order alongside ₹20,000 crore from Next-Gen Corvettes, and how are Zydus and Marico reshaping their growth models around US speciality launches and rural distribution?
Aftermarket Report: How did Nifty navigate a volatile session of sharp intraday swings to defend the 25,000 threshold and close at 25,045 as cooling crude oil prices offset overhead selling? And what do 12 gaining sectors led by PSU Banks surging 3.7%, seven consecutive sessions of foreign institutional buying, and the Fear & Greed Index climbing deeper into greed at 66 indicate despite weak market breadth?
Join us on WhatsApp, where we share interesting soundbites from concalls, articles, and everything else we come across throughout the day. You’ll also get notified the moment a new video or article drops so that you can read or watch it right away.
Thank you for reading. Do share this with your friends and make them as smart as you are 😉